Best Ways to Refinance Your Home Loan in Malaysia 2024
Refinancing a home loan in Malaysia can feel like a maze, especially when rates shift and banks roll out new packages each quarter. Yet the payoff—lower monthly payments, reduced interest over the loan’s life, or even cash‑out for renovations—can be well worth the effort. Below is a practical guide to the best options on the market right now, plus the key things you should weigh before signing the next agreement.
Why Consider Refinancing?
Most homeowners start thinking about refinancing when their current interest rate sits above the prevailing market level. A few percentage points can translate into thousands saved over ten years. Additionally, if you’ve built equity, a cash‑out refinance can fund home improvements, consolidate debt, or cover tuition without resorting to high‑interest credit cards.
But it isn’t just about the rate. Extending the loan tenure can ease cash flow, while shortening it can help you pay off the mortgage faster—though the monthly outlay will rise. Your personal financial goals dictate which angle makes the most sense.
Key Factors to Weigh Before You Switch
- Effective interest rate (EIR) – This includes the base rate plus any margin the bank applies. Compare the EIR rather than just the headline rate.
- Processing fees and legal costs – Some banks waive these for loyal customers, while others charge a flat fee that can erode savings.
- Early repayment penalties – If you’re still within the lock‑in period of your existing loan, breaking it early may attract a penalty of up to 2% of the outstanding balance.
- Loan‑to‑value (LTV) ratio – Lenders typically allow up to 90% of the property’s market value for a refinance, but this can vary with credit score and income stability.
- Flexibility of repayment options – Look for features like partial pre‑payment without charge, or the ability to switch between variable and fixed rates later on.
Top Refinancing Options in Malaysia
Bank Negara Malaysia’s recent policy adjustments have nudged many institutions to offer more competitive packages. Here are the most attractive choices as of 2024.
1. Fixed‑Rate Packages from Maybank and CIMB
Both Maybank and CIMB continue to dominate the fixed‑rate segment, offering tenures from three to five years with rates as low as 3.15% per annum for qualified borrowers. The advantage is predictability; your payment won’t budge even if the Base Rate rises.
These banks also provide a “Rate Lock” feature, allowing you to secure a rate for up to 30 days while you finalize documentation.
2. Variable‑Rate Plans from Public Bank and Hong Leong Bank
If you’re comfortable with market fluctuations, variable rates can be appealing. Public Bank’s “Flexi‑Rate” starts around 2.85% EIR, and Hong Leong’s “Smart Rate” offers a margin as low as 0.75% over the Base Rate.
Such plans often include the ability to switch to a fixed rate without penalty after a certain period, giving you a safety net if the market turns volatile.
3. Cash‑Out Refinancing from RHB and AmBank
For homeowners with solid equity, cash‑out options let you borrow up to 80% of the property’s current value. RHB’s “Home Equity Plus” and AmBank’s “Renovation Loan” both allow up to RM300,000 in cash, ideal for major upgrades or consolidating high‑interest debt.
Keep in mind that cash‑out loans usually carry a slightly higher interest rate—often 0.25% to 0.5% above standard refinancing rates—but the convenience can outweigh the marginal cost.
4. Islamic Financing Alternatives
Muslim borrowers or those preferring Sharia‑compliant products can explore Murabaha or Ijarah structures from banks like Bank Islam and Maybank Islamic. Rates are competitive, hovering around 3.30% EIR, and the contracts avoid interest altogether, using profit‑margin models instead.
These products also often feature flexible early settlement terms, making them a viable option for many families.
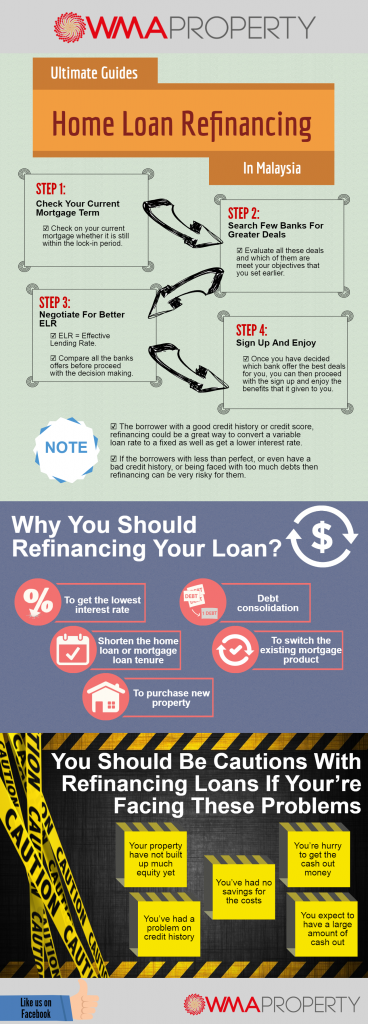
Step‑by‑Step Guide to Apply
1. Assess your current loan: Note the outstanding balance, remaining tenure, and any early repayment fees.
2. Gather documentation: Recent payslips, tax returns, the original title deed, and a valuation report (some banks will arrange this for you).
3. Compare offers: Use online calculators from the banks’ websites or independent portals to see the net savings after fees.
4. Submit the application: Most banks now offer a digital submission process; you’ll receive a provisional approval within a week.
5. Complete legal formalities: Once approved, the bank will handle the discharge of your existing loan and the registration of the new mortgage at the Land Office.
6. Start the new repayment schedule: Verify the first payment date and ensure the amount aligns with your budgeting plan.
Common Pitfalls to Avoid
Many borrowers get caught off guard by hidden costs. Always ask for a breakdown of all fees before committing. Also, don’t let a lower rate blind you to a longer tenure that could increase total interest paid.
Lastly, be wary of “one‑size‑fits‑all” promotions. A package that looks great on paper may not suit your cash‑flow needs if it forces you into a fixed rate that’s higher than the market’s average after the first year.
Frequently Asked Questions
Can I refinance if I’m still within the lock‑in period of my current loan?
Yes, but you’ll likely incur an early repayment penalty from your existing lender. Weigh this cost against the potential savings from a lower rate; sometimes the net benefit is still positive.
Do I need a new property valuation for every refinance?
Most banks require a fresh valuation, especially if you’re seeking a cash‑out loan. However, some institutions waive the fee if the loan‑to‑value ratio stays below 80% and you have a good credit record.
Is a variable‑rate loan riskier than a fixed‑rate loan?
Variable rates move with the Base Rate, so they can rise if the economy tightens. The risk can be mitigated by choosing a bank that offers a free rate‑switch after a set period, giving you an exit strategy if rates climb sharply.
What documents are essential for an Islamic home loan refinance?
Besides the standard financial paperwork, you’ll need to sign a Murabaha or Ijarah agreement outlining the profit margin. The process mirrors conventional refinancing, but the contract language reflects Sharia principles.