Can You Actually Waive the Financing Contingency With iBuyers?
If you’ve listed your home with an iBuyer, you’ve probably heard the phrase “waive the financing contingency.” It sounds like a shortcut to a quicker sale, but it also raises a lot of questions. Can you really skip that safety net? What does it mean for your pocketbook if the buyer’s loan falls through? Below we break down the mechanics, the risks, and the moments when waiving might actually be a savvy move.
What Is a Financing Contingency, Anyway?
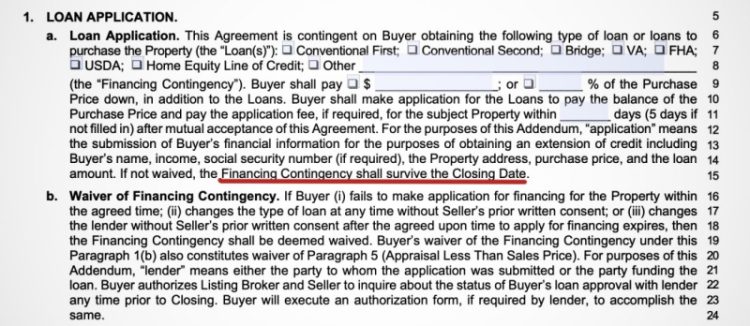
A financing contingency is a clause in a purchase agreement that lets the buyer back out—without penalty—if their mortgage doesn’t get approved. In a traditional sale, that clause protects both parties: the buyer isn’t forced into a loan they can’t afford, and the seller keeps the deal alive until the loan is solid.
When you work with an iBuyer, the process looks different. iBuyers are companies that make cash offers on homes, often closing within days. Because they’re not relying on a third‑party lender, many iBuyers present an “all‑cash” offer that technically doesn’t need a financing contingency at all.
How iBuyers Structure Their Offers
iBuyers typically use a two‑step model. First, they issue a preliminary, often‑online, offer based on public data and a quick home appraisal. If you accept, they conduct a more thorough inspection and finalize the price. Throughout, the payment is framed as cash—even though the iBuyer may later fund the purchase with a line of credit or a portfolio loan.
Because the iBuyer’s funding is internal, the contract often omits the traditional financing contingency. From a legal standpoint, you’re not “waiving” a clause that never existed; you’re simply agreeing to the iBuyer’s cash‑funded purchase structure.
Why Sellers Might Want to Waive the Contingency
- Speed. Without a financing clause, the closing timeline can shrink to as little as seven days.
- Certainty. iBuyers rarely back out once they’ve signed the purchase contract, reducing the anxiety of a buyer’s loan denial.
- Convenience. The iBuyer often handles paperwork, repairs, and even moving logistics, turning a potentially stressful process into a “set‑and‑forget” transaction.
Those benefits can be especially appealing if you’re relocating for a job, need to free up cash quickly, or simply prefer a hassle‑free sale.
The Risks of Skipping the Safety Net
Even though iBuyers are funded by large companies, the reality is that they still rely on financing—just not yours. If the iBuyer’s own credit line runs dry or market conditions shift, they could walk away, leaving you with a broken contract. In that scenario, you might have to re‑list the home, potentially at a lower price after the market has moved.
Another subtle risk is the offer amount. Because iBuyers aim for a quick turnaround and a profit margin, their cash offers often sit a few percent below market value. By waiving the financing contingency, you’re essentially accepting that trade‑off for speed.
When Waiving Might Actually Make Sense
It’s not a one‑size‑fits‑all decision. Consider waiving only if:
- You have a firm relocation deadline and can’t afford a prolonged listing period.
- The iBuyer’s offer is close to—or above—what you’d expect after accounting for repair costs and closing fees.
- You’ve vetted the iBuyer’s reputation, read reviews, and confirmed they have a solid track record of closing deals.
In those cases, the convenience factor can outweigh the modest discount you might receive from a conventional buyer who needs a mortgage.
Practical Tips Before Signing Anything
- Read the fine print. Look for any “funding contingency” language that might give the iBuyer an out.
- Ask about the funding source. Reputable iBuyers will disclose whether they use internal capital, a line of credit, or a partnership with a bank.
- Negotiate repairs. Since iBuyers often base offers on a quick visual assessment, you can sometimes negotiate a higher price by providing a detailed repair estimate.
- Keep a backup plan. Have a contingency in mind—like listing on the MLS—if the iBuyer’s deal falls through.
These steps help you protect yourself while still enjoying the speed that iBuyers promise.
Frequently Asked Questions
Do iBuyers ever actually need a financing contingency?
Not in the traditional sense. Their offers are presented as cash, but they may still rely on internal financing that could fail under extreme market stress.
Can I negotiate the price after waiving the contingency?
Yes, you can still discuss repairs, inspection findings, or market comps. Waiving the financing clause doesn’t lock you into the initial figure.
What happens if the iBuyer backs out after I’ve waived the contingency?
Typically, the contract will include a clause that allows you to relist the property. You may face a short waiting period before you can accept another offer.
Is waiving the financing contingency a good idea for first‑time sellers?
It depends on your timeline and risk tolerance. First‑time sellers who value certainty and speed often find it worthwhile, but they should weigh the lower offer against the peace of mind a traditional buyer provides.