How ASEAN’s New Payments Policy Will Shape Regional Commerce
The region’s payment landscape has been shifting fast, and the ASEAN Payments Policy is the latest wave of regulatory change that could change how merchants, banks, and everyday users transact across Southeast Asia. While the policy’s details are technical, its core idea is simple: make cross‑border payments cheaper, faster, and more reliable for everyone in the bloc.
What the ASEAN Payments Policy Is About
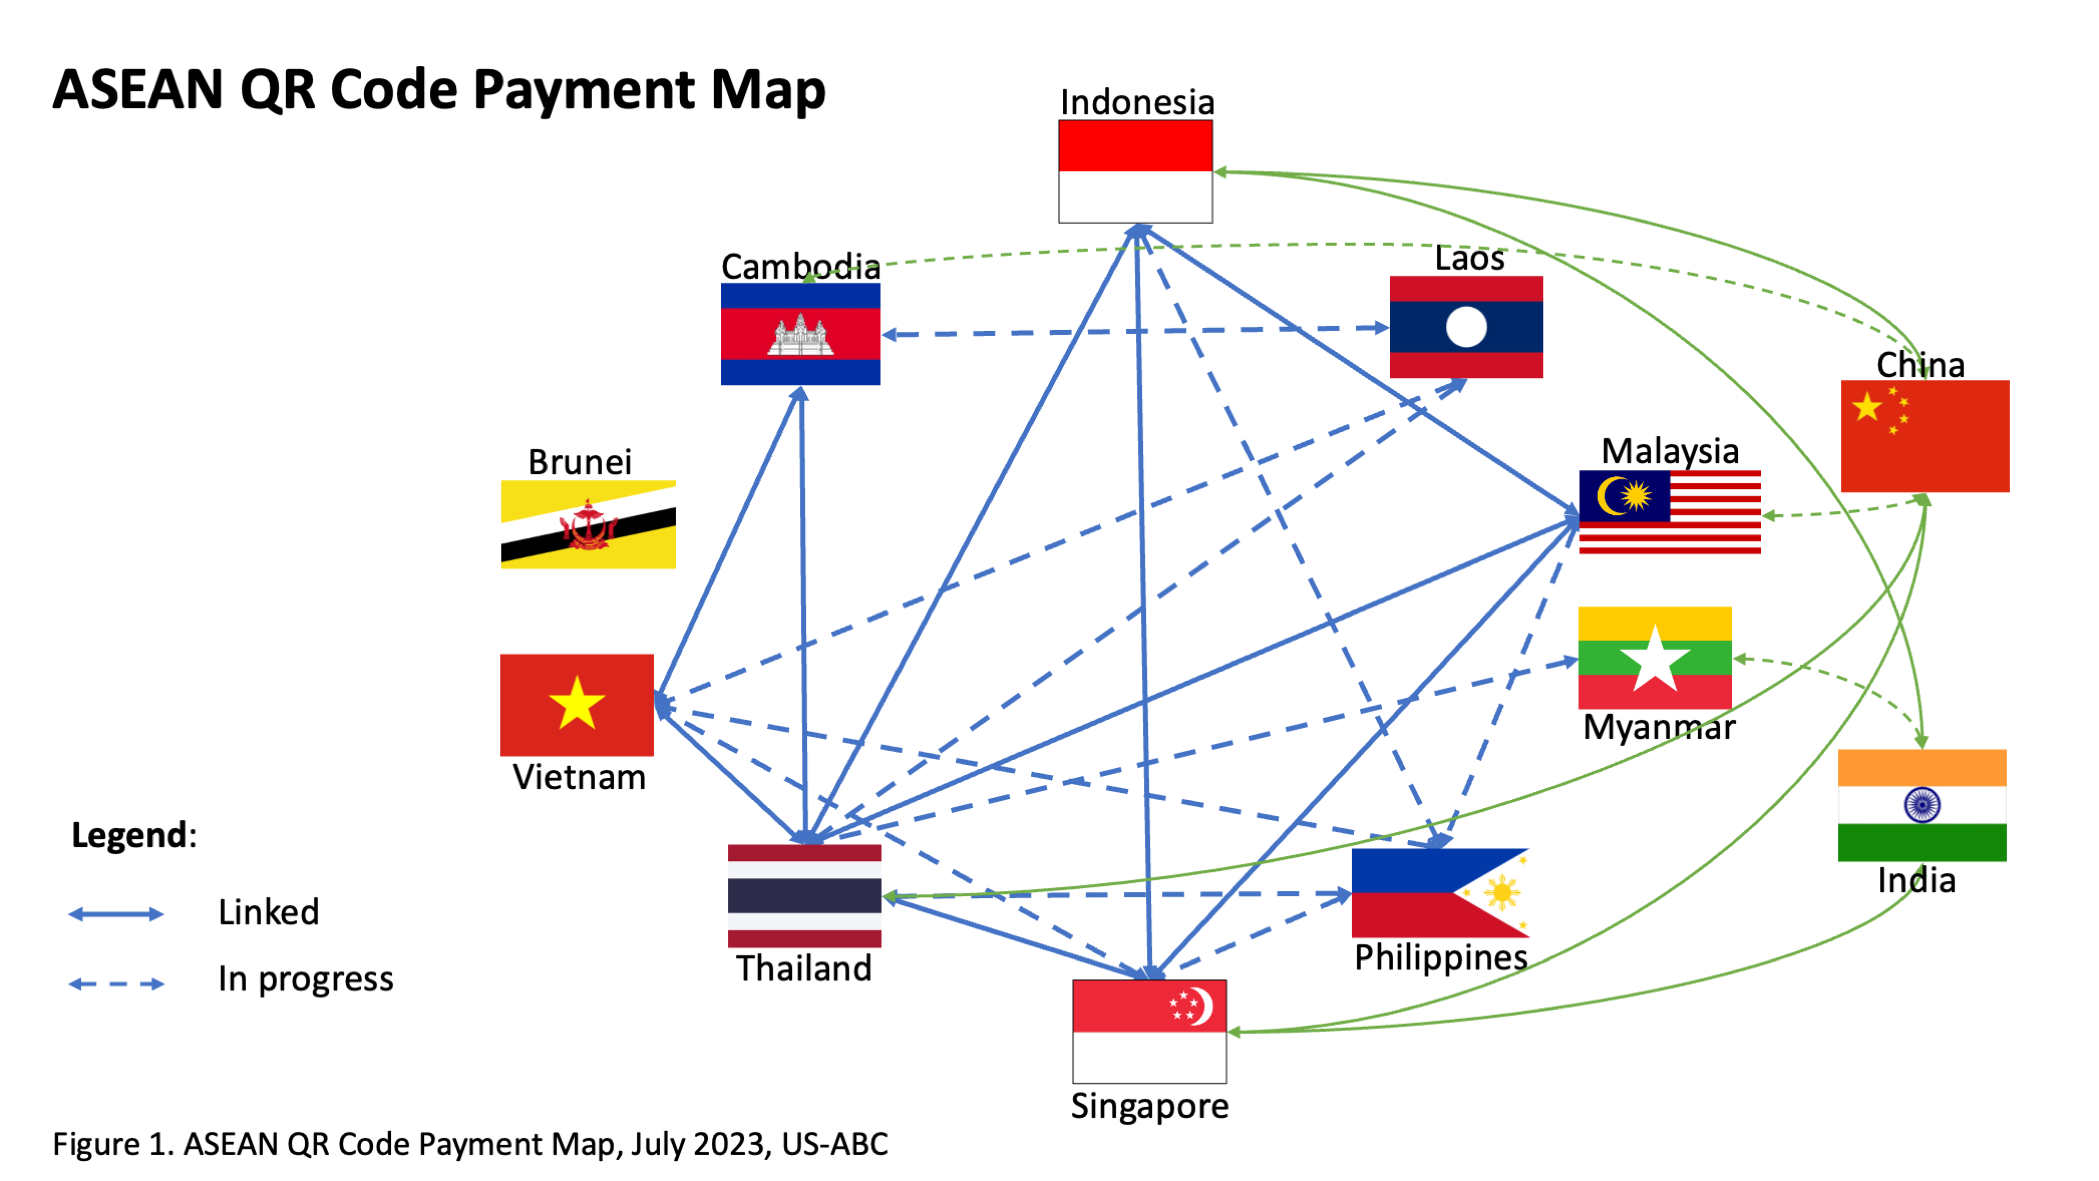
At its heart, the policy is a set of rules and standards that all member states agree to follow when they run payment systems. Think of it as a common operating system that lets a local bank in Vietnam send money to a store in Singapore with the same security and speed it uses for domestic transactions. The aim is to eliminate hidden fees, reduce settlement delays, and create a single, trusted payment infrastructure that supports both retail and wholesale flows.
Key Pillars of the Policy
The policy is built around five main pillars that guide how payment services should work:
- Interoperability – Payment methods must be able to talk to one another across borders, using open APIs and shared standards.
- Transparency – Fees, exchange rates, and processing times must be disclosed clearly to prevent surprise costs.
- Security and Resilience – A unified set of cyber‑security protocols protects against fraud and downtime.
- Innovation and Inclusion – The framework encourages fintech startups and encourages digital wallets, QR codes, and other modern tools.
- Consumer Protection – Strong recourse mechanisms are put in place for disputes and unauthorized transactions.
How It Affects Businesses and Consumers
For merchants, the policy means fewer payment gateways to integrate. One API call can cover all ASEAN markets, cutting development costs. Small retailers in rural Thailand, for example, can accept card payments from tourists in Malaysia without having to sign multiple contracts.
Consumers, on the other hand, will notice a smoother experience. A payment that used to take days to settle between Jakarta and Manila could be completed in minutes, with exchange rates that reflect real‑time market data instead of opaque inter‑bank spreads.
Digital Currencies and Central Bank Issued Digital Currencies
The policy also lays groundwork for the potential use of Central Bank Digital Currencies (CBDCs) across the bloc. If a group of countries issues compatible CBDCs, the policy would provide the rules for how they can settle with each other, reducing the need for foreign currency intermediaries.
Implementation Timeline and Challenges
Implementation is rolling out in phases. By 2025, member states are expected to align their national payment clearing systems with the new interoperability standards. By 2027, cross‑border real‑time settlement will be fully operational for retail transactions, and by 2030 the policy will include full CBDC integration.
Challenges remain. Aligning 10 different national regulations requires coordination and sometimes compromises. Smaller economies may struggle with the technical investment needed to upgrade legacy systems. Nevertheless, the policy includes capacity‑building funds and technical support from the ASEAN Secretariat to help bridge these gaps.
FAQ
Q: Will the ASEAN Payments Policy affect my local bank’s fees?
A: Yes. The policy mandates transparent fee structures, so banks will need to disclose charges upfront and can no longer bundle fees in opaque ways.
Q: Can I use my existing digital wallet for cross‑border payments?
A: Existing wallets that adopt the new open‑API standards can operate across borders without needing additional approvals.
Q: Does the policy cover only retail payments, or also wholesale transactions?
A: The policy addresses both, but wholesale settlement is targeted for implementation a bit later, around 2028.
Q: How does the policy help fintech startups?
A: By standardizing APIs and reducing compliance friction, startups can launch products faster and reach customers in multiple ASEAN markets with a single integration.