How Hyundai Capital America Simplifies Auto Financing
Understanding Hyundai Capital America’s Role in Your Car Purchase
When you walk onto a dealership floor, the financing conversation often feels like a separate maze. Hyundai Capital America (HMF) steps in as the lender that powers many of those financing offers, turning a complicated process into a more straightforward one. As a subsidiary of Hyundai Motor Group, HMF focuses on providing flexible loan and lease options tailored to a range of credit profiles.
In practice, the company works hand‑in‑hand with Hyundai and Kia dealers across the United States, handling everything from credit approvals to monthly payment calculations. This partnership means that the numbers you see on the lot are usually already vetted by HMF, reducing the back‑and‑forth that typically accompanies auto loans.
Key Financing Products Offered by HMF
HMF doesn’t rely on a one‑size‑fits‑all approach. Instead, it offers several distinct products that can match your financial situation and driving habits.
- Traditional Installment Loans – Fixed‑rate loans that let you own the vehicle outright once the term ends. Payments are predictable, and you can choose terms from 24 to 72 months.
- Lease Programs – Ideal for drivers who prefer a new car every few years. Lease payments are generally lower than loan payments, and HMF often includes mileage allowances and wear‑and‑tear protection.
- Hyundai Capital Smart Finance – A hybrid option that blends features of a loan and a lease, allowing you to return the vehicle early with limited penalties.
Each product comes with its own set of incentives, such as introductory APRs for well‑qualified borrowers or loyalty discounts for returning Hyundai owners.
Eligibility: Who Can Qualify?
One of HMF’s selling points is its willingness to work with a broad spectrum of credit scores. While a stellar credit rating will net you the lowest rates, the company also offers programs for those rebuilding credit.
Typical eligibility factors include:
- Credit score (generally 620+ for standard rates, though lower scores may still be approved with higher APRs)
- Debt‑to‑income ratio (a lower ratio improves approval odds)
- Employment stability (steady income sources are a plus)
- Down payment amount (a larger down payment can offset a weaker credit profile)
Because HMF evaluates applications on a case‑by‑case basis, it’s worth applying even if you’re unsure about your credit standing.
How the Application Process Works
The steps are designed to be dealer‑friendly, which translates to a smoother experience for you.
- Submit an Application – Most dealerships have a digital portal that sends your information directly to HMF.
- Credit Review – HMF runs a soft or hard inquiry (depending on the dealer’s setup) and evaluates the data against its internal guidelines.
- Offer Presentation – Within minutes to a few hours, you’ll receive a financing quote that includes the APR, term length, and monthly payment.
- Finalize the Deal – If you accept, you’ll sign the loan or lease agreement, and the paperwork is processed electronically.
Because the lender is already integrated with the dealer’s system, you rarely have to chase down additional documents after the initial application.
Understanding the Numbers: APR, Terms, and Fees
Auto financing jargon can be intimidating, but breaking it down helps you compare offers more confidently.
- APR (Annual Percentage Rate) – This is the true cost of borrowing, incorporating interest and any lender fees. A lower APR means lower overall cost.
- Loan Term – The number of months you’ll be making payments. Shorter terms increase monthly payments but reduce total interest paid.
- Down Payment – Money you put up front, which directly reduces the amount you finance.
- Fees – HMF may charge an acquisition fee (common with leases) or a documentation fee. These are usually disclosed upfront.
When reviewing an HMF offer, ask the dealer to break down each component so you can see exactly where your money is going.
Benefits of Choosing Hyundai Capital America
Beyond the basic loan mechanics, HMF brings a few notable perks to the table.
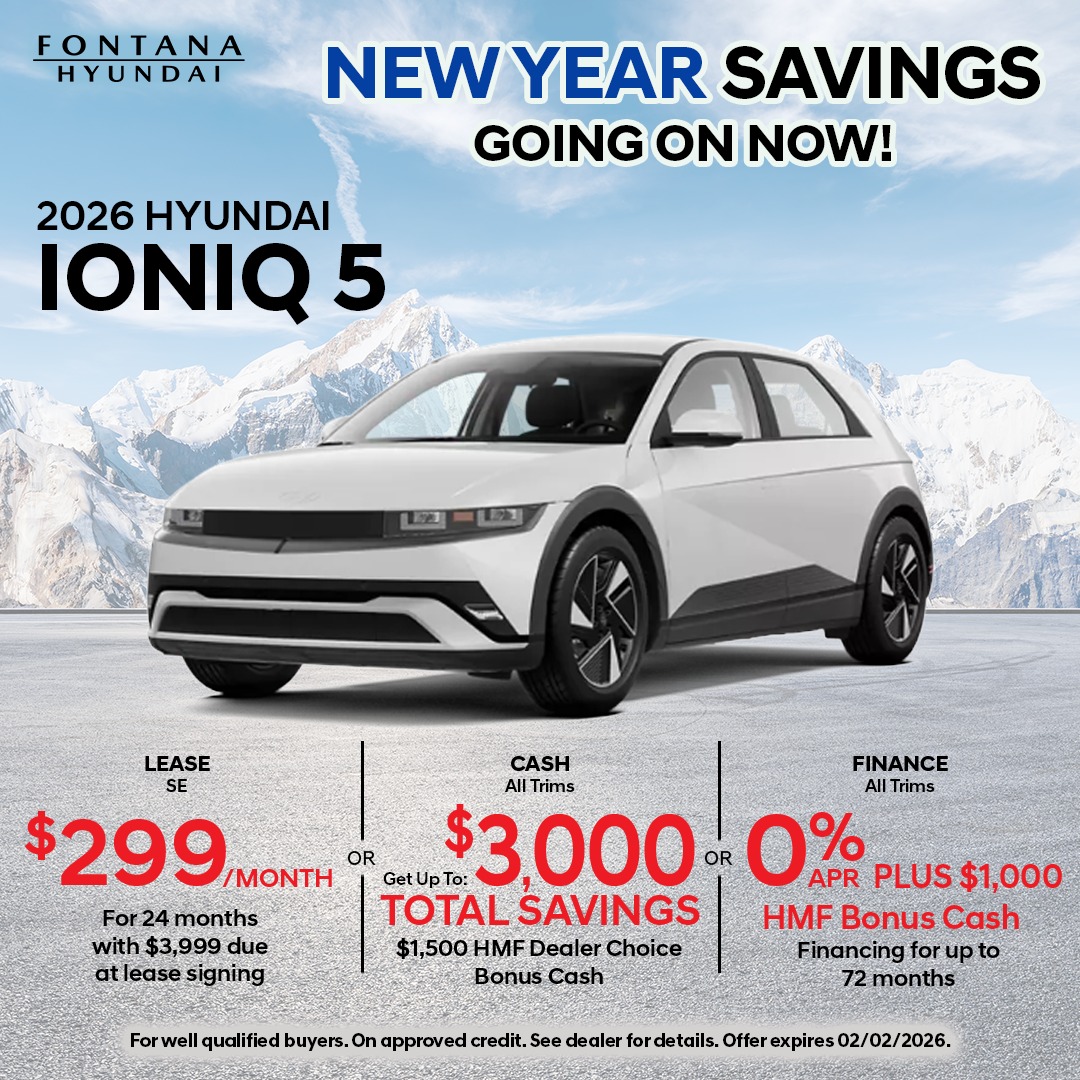
- Special Incentives – Seasonal promotions, such as 0% APR for qualified buyers on select models, are often funded directly by HMF.
- Customer Service Integration – Because HMF works exclusively with Hyundai and Kia dealers, you get a single point of contact for both financing and vehicle service questions.
- Online Account Management – A dedicated portal lets you view balances, make payments, and request payoff statements without calling.
- Flexibility for Early Payoff – Most HMF loans allow you to pay off early without hefty prepayment penalties, giving you control over your debt.
Potential Drawbacks to Keep in Mind
No financing option is flawless. Some drivers find that HMF’s rates, while competitive, can be slightly higher than those offered by large banks for borrowers with excellent credit. Additionally, lease mileage limits can be restrictive if you exceed the allotted miles.
It’s also worth noting that while HMF offers a “quick‑approval” experience, the final approval still hinges on a thorough credit assessment. If you’re applying with a borderline score, be prepared for a possible higher APR or a request for a larger down payment.
Tips for Getting the Best Deal with HMF
Armed with this background, you can approach your financing conversation strategically.
- Shop around for manufacturer incentives before stepping onto the lot; those promotions often stack with HMF’s own offers.
- Consider a modest down payment (10‑20% of the vehicle price) to lower your APR and monthly payment.
- Ask about “gap insurance” if you’re leasing; HMF sometimes bundles it at a reduced rate.
- Review the contract for any hidden fees—especially acquisition fees on leases.
- If you have a strong credit score, negotiate the APR; dealerships have some leeway in setting the final rate.
Frequently Asked Questions
Can I finance a used Hyundai through HMF?
Yes. While HMF is best known for new‑car financing, it also offers loans for certified pre‑owned Hyundai and Kia models, usually with slightly higher rates than new‑car loans.
What happens if I miss a payment?
HMF treats missed payments similarly to other lenders: a late fee is applied, and the account may be reported to credit bureaus after 30 days. Contacting HMF promptly can sometimes result in a payment deferral or restructuring.
Is it possible to refinance an existing HMF loan?
Refinancing is permitted, though you’ll need to meet the new lender’s credit criteria. Many borrowers refinance to take advantage of lower market rates after an initial high‑interest period.
Do I need a co‑signer to qualify?
A co‑signer can improve your approval odds, especially if your credit history is limited. HMF evaluates the co‑signer’s credit separately, and a strong co‑signer can secure a better APR.