How Low Can FHA Refinance Rates Get? A Practical Savings Guide
Every homeowner with an FHA-backed loan wants to know whether the current market offers a chance to lower their monthly payment. The key lies in understanding FHA refinance mortgage rates—the rates that determine the new loan’s cost. In this guide, we break down what these rates are, how they’re calculated, and how you can spot the best deal to maximize your savings.
What Are FHA Refinance Mortgage Rates?
FHA refinance rates are the interest rates offered to borrowers who replace an existing FHA loan with a new one, either through a streamlined refinance or a cash‑out refinance. The goal is to either reduce the monthly payment, shorten the loan term, or pull cash from the home’s equity.
Unlike conventional rates, FHA rates often incorporate a government-backed risk premium. The actual rate a borrower receives depends on the lender’s underwriting, the borrower’s credit profile, and the prevailing market conditions.
Streamline vs. Cash‑Out Refinance
- Streamline refinance – Uses the existing FHA loan’s documentation with minimal credit or income verification. It’s ideal for lowering the interest rate or switching to a fixed‑rate loan.
- Cash‑out refinance – Allows homeowners to borrow against the equity in their home, giving them a lump sum of cash while refinancing the original loan.
Factors That Influence Your Rate
- Credit score – A higher score typically yields a lower rate.
- Debt‑to‑income ratio – Lenders consider how much of your income goes toward existing debts.
- Loan-to‑value ratio (LTV) – The higher the LTV, the greater the risk and often the higher the rate.
- Current market interest trends – Rates rise and fall with the broader economic environment.
- Loan amount and term – Larger loans and longer terms can shift the rate offered.
How to Find the Best FHA Refinance Rates Today
Finding a competitive rate requires more than just checking a single lender’s website. Consider these tactics:
- Shop around – Compare rates from at least three different lenders, including banks, credit unions, and online mortgage specialists.
- Use rate comparison tools – Many financial websites aggregate real‑time rates and allow you to filter by FHA refinance.
- Ask about rate locks – Securing a rate lock early protects you from sudden market increases.
- Timing matters – Rates often dip at the beginning of the year or during economic downturns.
The Savings Equation: Calculating Potential Monthly & Lifetime Gains
Let’s walk through a typical calculation to illustrate the impact of an FHA refinance.
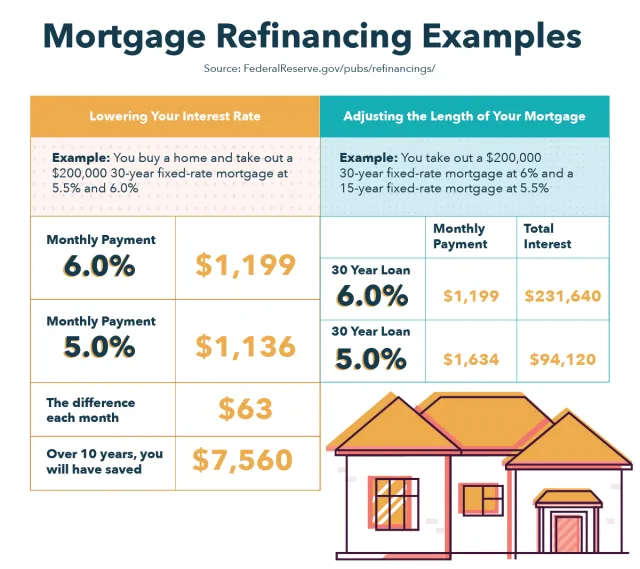
Suppose you have a 30‑year FHA loan with a 3.75% rate, a balance of $200,000, and a remaining term of 25 years. If you refinance to a 2.75% rate, your new monthly payment drops from about $975 to $890, a $85 monthly savings.
Over the remaining 25 years, that $85 translates to roughly $25,500 in total savings, not accounting for the costs of refinancing. If you can negotiate a lower rate or a shorter loan term, the savings grow even larger.
Common Misconceptions About FHA Refinance
- “FHA rates are always lower than conventional rates.” – Not true; rates depend on market conditions and the lender’s fee structure.
- “You can refinance any time.” – While you can refinance anytime, some lenders impose a waiting period after the original loan’s origination.
- “A cash‑out refinance always yields a better deal.” – Pulling cash increases the loan balance, potentially raising the rate and monthly payment.
Steps to Apply for an FHA Refinance
- Gather necessary documentation: recent pay stubs, tax returns, credit report, and property appraisal.
- Get pre‑qualification from multiple lenders to see the rates you qualify for.
- Choose between streamline or cash‑out, depending on your goal.
- Submit the formal application and any required collateral or documentation.
- Attend the appraisal and title search, if required.
- Review the closing disclosure, verify the interest rate, points, and closing costs.
- Sign the loan documents, pay the closing costs, and receive your new mortgage.
When Is It Worth It?
Consider refinancing when:
- The new interest rate is at least 0.25% lower than your current rate.
- Monthly savings exceed the total closing costs over the life of the loan.
- You plan to stay in the house for at least the remaining term of the new loan.
- You’re comfortable taking on a slightly higher monthly payment in exchange for a shorter loan term.
FAQ
- What is the difference between an FHA streamline refinance and a conventional refinance? A streamline refinance uses less documentation and can be faster, but may have higher rates; conventional refinancing can offer more flexibility in terms and potentially lower rates if your credit is strong.
- Do I need a home appraisal for an FHA refinance? Typically, yes—especially for cash‑out refinances—to determine the current value and available equity.
- How long does the FHA refinance process take? From application to closing, the process usually takes 30 to 45 days, depending on lender workload and appraisal availability.
- Can I refinance an FHA loan if my credit score is low? You can, but your rate may be higher. Some lenders specialize in low‑score FHA refinances, offering competitive terms.