How the FDIC Steps In When a Bank Fails and What Happens Next
When a bank’s doors close, most people worry about losing their savings or seeing their accounts freeze overnight. In reality, a federal safety net is already in place: the FDIC steps in when a bank fails, safeguarding depositors and preserving confidence in the financial system. The process is designed to be swift, transparent, and minimally disruptive.
Who Is the FDIC and What Is Its Mission?
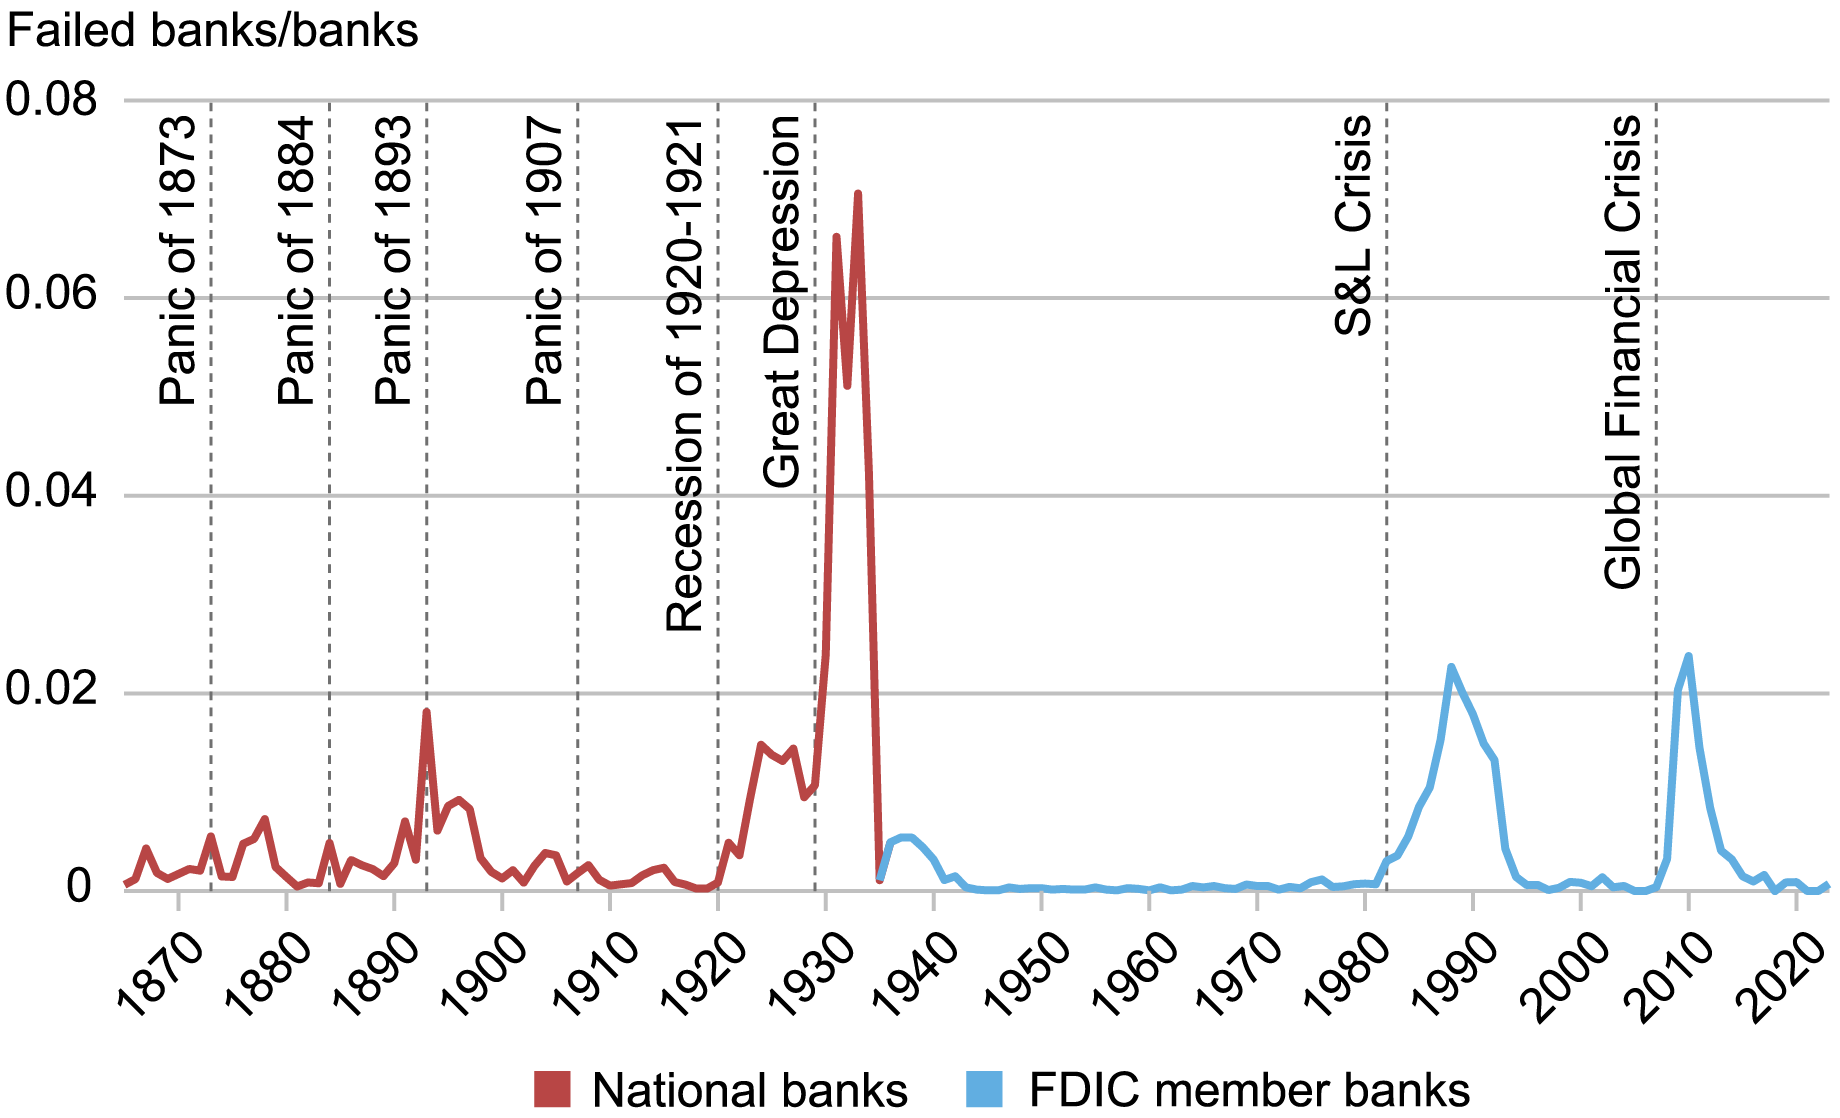
The FDIC is an independent federal agency created in 1933 during the Great Depression. Its core mission is to maintain public confidence by insuring deposits, examining and supervising banks, and managing receiverships when institutions fail. Unlike a typical insurance company, the FDIC’s funding comes from premiums paid by insured banks, not taxpayers.
When a Bank is Declared Insolvent, the FDIC Steps In Immediately
Once a bank’s financial health deteriorates to a point where it can no longer meet its obligations, regulators trigger a “failure” event. The FDIC’s first responsibility is to step in and take control of the bank’s assets and liabilities, a process called a receiver. This hands the institution over from the failed bank’s management to the FDIC, ensuring orderly administration.
The Insurance Process Explained
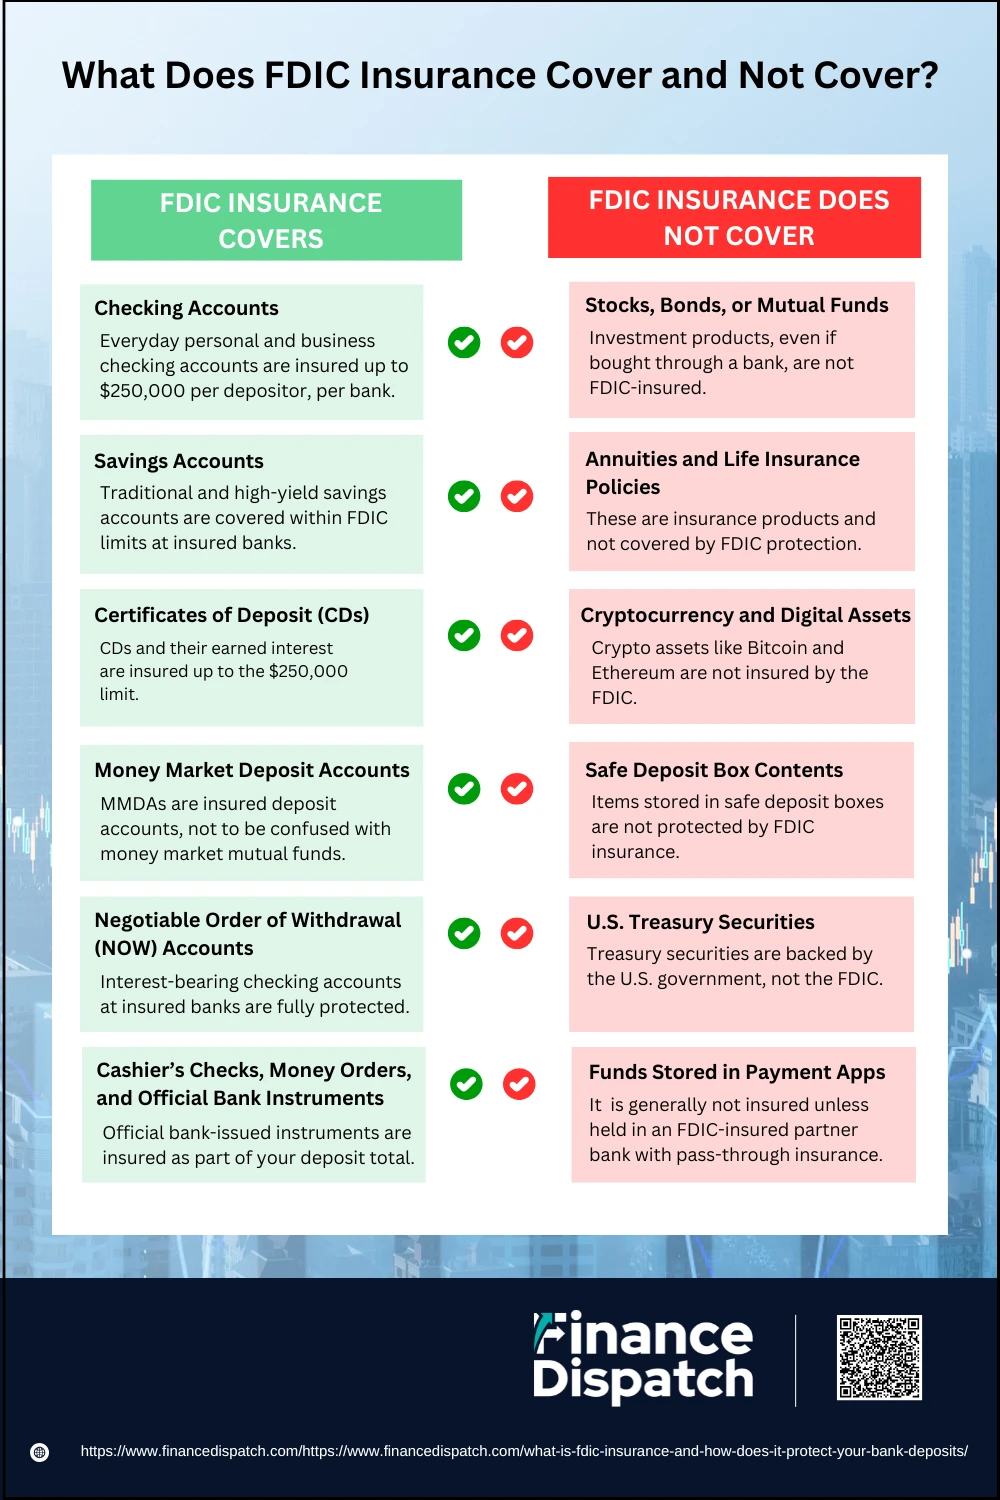
Deposit insurance protects up to $250,000 per depositor per insured bank. When a bank fails:
- The FDIC quickly verifies the insured amounts.
- Depositors receive payment within 10 days of the bank’s closure, usually via electronic transfer or a replacement check.
- Uninsured balances are handled on a case‑by‑case basis, often through liquidation of assets.
Because the FDIC’s insurance fund is built from the industry’s contributions, depositors can be confident that most of their money is returned promptly.
How the FDIC Chooses a Successor Institution
Rather than liquidating a bank outright, the FDIC frequently arranges a sale to another financial institution. The steps involve:
- Assessment: The FDIC evaluates the failed bank’s assets, liabilities, and customer base.
- Market Search: Potential buyers, usually larger banks, are invited to submit proposals.
- Negotiation: The FDIC negotiates terms that preserve as many services as possible for customers.
- Approval: The final deal is approved by the FDIC Board and the bank’s shareholders.
If no buyer emerges, the FDIC may proceed with a liquidation, selling off the bank’s assets to repay depositors and creditors.
What Customers Should Expect
Customers of a failed bank are typically not surprised by the FDIC’s involvement. Common scenarios include:
- Accounts remain active on the same bank’s online platform, but under the new owner.
- Credit card and loan contracts transfer to the buying institution with no change in terms.
- Some services, like foreign currency accounts or specialized investment products, may shift to another provider.
- Customers are notified via mail, email, and phone calls about the transition.
In short, day‑to‑day banking operations continue with minimal interruption.
Regulatory Oversight During the Receiver Phase
The FDIC’s receivership powers are comprehensive. It can:
- Sell or dispose of real estate, securities, and other assets.
- Hire legal counsel to pursue claims against former executives or owners.
- Ensure that the bank’s records are preserved for audits.
- Coordinate with other agencies, such as the Federal Reserve and the Office of the Comptroller of the Currency.
These measures prevent a failure from triggering a broader systemic crisis.
Case Study: The 2009 Failure of Wachovia’s Sub‑Branch Network
In 2008, the collapse of the U.S. housing market led to the failure of numerous banks. When Wachovia’s small‑branch network faltered, the FDIC took over and sold the network to Bank of America in 2009. The transfer was completed in less than a month, and customers continued to access their accounts without interruption.
That example illustrates how the FDIC’s rapid response can preserve the everyday financial habits of millions.
Why the FDIC’s Role Matters to the Economy
A bank failure can spread panic, prompting depositors at other institutions to withdraw funds. The FDIC’s quick insurance payments and orderly receiverships keep the money in circulation, preventing a credit crunch. In addition, the FDIC’s supervisory work identifies risky banks early, reducing the likelihood of future failures.
By ensuring that depositors are protected and that failing banks are handled responsibly, the FDIC maintains both individual financial security and overall market stability.
FAQ
- What happens to my savings if the bank I use fails? Deposit insurance covers up to $250,000 per depositor. You should receive payment within about 10 days after the bank’s closure.
- Can I transfer my account to another bank after a failure? Yes. The FDIC typically arranges for a successor bank to absorb the failed institution’s deposits, and you can keep your account number or transfer to a new one at your discretion.
- Will my credit score be affected if my bank fails? No. The FDIC’s insurance protects deposits, but credit scores are unaffected unless you had outstanding loans that defaulted.