How to Grab the Best Ford Mustang Finance Deals Today
Looking to drive a roaring Ford Mustang without breaking the bank? It’s all about the right finance plan. Ford Mustang Finance Deals are more than just low interest rates; they’re a mix of incentives, loyalty programs, and timing that can shave hundreds off your monthly payment. This guide will walk you through the most effective ways to lock in the best offers, whether you’re buying new or used.
Why Timing Matters for Ford Mustang Finance Deals
Car manufacturers, especially Ford, rotate incentives every quarter. Sales staff often push last‑month models to clear inventory, meaning you can snag a Mustang that’s still a new model year at a reduced price or with an added bonus. Keep an eye on:
- End‑of‑quarter sales events
- Manufacturer holiday promotions (e.g., Black Friday, Labor Day)
- New model releases—dealers want space for the next generation
Understand the Core Components of a Finance Deal
A solid deal is built on three pillars:
- APR (Annual Percentage Rate): The interest you’ll pay over the life of the loan. Even a half‑percentage point difference can save thousands.
- Down Payment: A larger upfront payment reduces monthly costs and overall interest.
- Trade‑in Value: Leveraging the value of your current vehicle can offset the new car’s price.
Always ask for a breakdown sheet that lists each element, so you can compare offers side‑by‑side.
Leverage Credit Builder Programs and Loyalty Incentives
Ford offers Ford Credit and Ford Loyalty programs that can lower APR or provide cashback for returning customers. If you’ve purchased a Ford before, or if you’re a student or military personnel, you may qualify for additional savings. Don’t forget:
- Student discount: up to 1% off the APR for enrolled students
- Military discount: extra cashback or lower financing rates for active or retired personnel
- Previous Ford buyer incentive: typically 0.5% off the APR or a $500 bonus
Consider Lease vs. Loan: Which Saves You More?
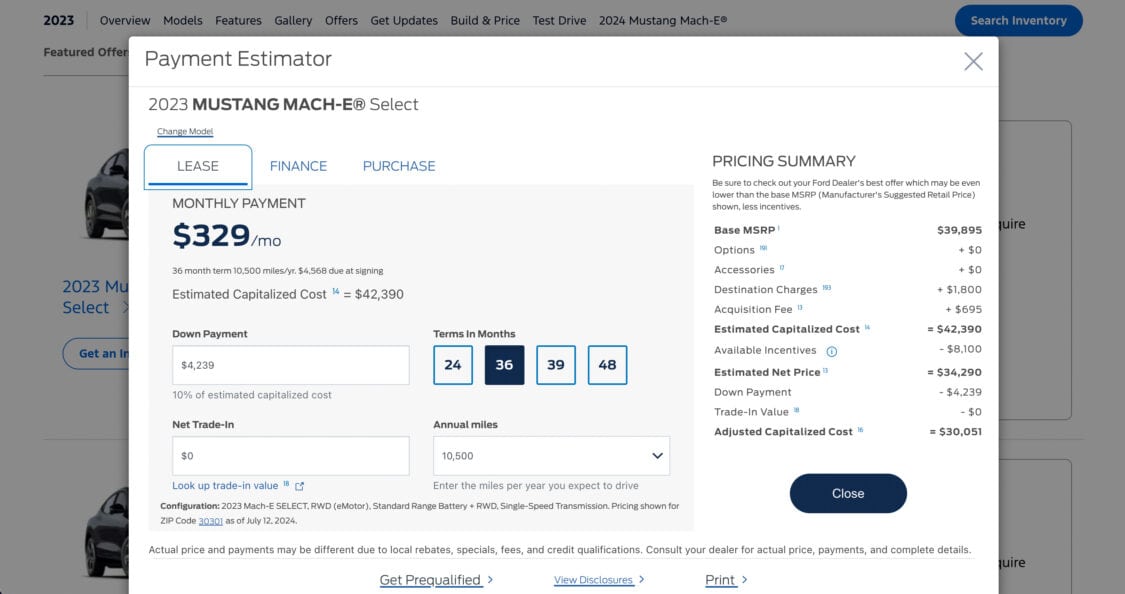
Leasing a Mustang often results in lower monthly payments because you’re essentially paying for depreciation, not full ownership. However, leases come with mileage caps, wear‑and‑tear penalties, and no equity at the end of the term. Loans allow you to build equity but might carry higher monthly costs. Use a simple calculator to compare total out‑of‑pocket costs for the first three to five years.
Key Questions When Comparing Lease and Loan
• How many miles do you drive yearly?
• Do you want to own the car eventually?
• Are you comfortable with mileage penalties?
• Do you prefer a lower monthly payment or lower overall cost?
Negotiate Like a Pro: Strategies That Work
1. Do Your Homework – Research MSRP, invoice price, and the current market value of the Mustang. Sites like Edmunds, Kelley Blue Book, and the NADA guide can help.
2. Ask About Incentives – Inquire about dealer rebates, cash back offers, and any manufacturer incentives that haven’t been advertised.
3. Bring a Competing Quote – A competing dealer’s offer can give you leverage to match or beat it.
4. Keep Your Credit Score in Check – A higher credit score locks you into lower APRs. If your score is low, consider a cosigner or a secured loan to improve terms.
5. Read the Fine Print – Watch for add‑ons like extended warranties, GAP insurance, and maintenance packages that can inflate the overall cost.
Utilize Online Tools and Dealership Apps
Many dealerships now offer an online pre‑approval process. This allows you to secure an APR before you even visit the lot, giving you bargaining power. Additionally, apps like the Ford Mobile App provide instant alerts for flash deals and price drops.
Know the Total Cost of Ownership
Beyond the monthly payment, consider fuel efficiency, maintenance, insurance, and depreciation. A Mustang’s high-performance variants can cost more in fuel and insurance. Calculators on the Ford website can give you a realistic estimate of long‑term expenses.
FAQs About Ford Mustang Finance Deals
- What credit score do I need for a Mustang finance? A credit score of 680 or higher typically qualifies for the best APRs, but scores as low as 620 can still secure financing with a higher rate or a larger down payment.
- Can I trade in my old car to lower the Mustang price? Yes—trade‑in values are factored into the new purchase price and can reduce the amount you need to finance.
- What is the typical down payment for a Mustang? Most buyers put down 10–20% of the vehicle’s price, though it can be as low as 0% if you qualify for a special promotion.
- Is leasing better than buying? Leasing often offers lower monthly payments and flexibility, but you’ll never own the car. Buying builds equity, which can be valuable if you plan to keep it long‑term.
Armed with these insights, you’ll be ready to negotiate confidently and secure the best Ford Mustang Finance Deals that align with your budget and driving goals. Remember, the key is timing, research, and a willingness to walk away if an offer doesn’t meet your standards. Happy hunting—may your Mustang’s roar be as satisfying as the savings in your wallet!