How to Pre‑Qualify for a Capital One Auto Navigator Car Loan
What the Auto Navigator Program Actually Offers
If you’re hunting for a new ride and want to keep the financing conversation low‑key, you’ve probably heard of Capital One’s Auto Navigator. It’s a web‑based marketplace that lets you browse inventory, compare rates, and—crucially—run a quick pre‑qualification without a hard credit pull. In plain English, pre‑qualification gives you a ballpark idea of what you might qualify for, helping you set realistic expectations before you step onto the dealer floor.
Understanding Car Loan Pre‑Qualification
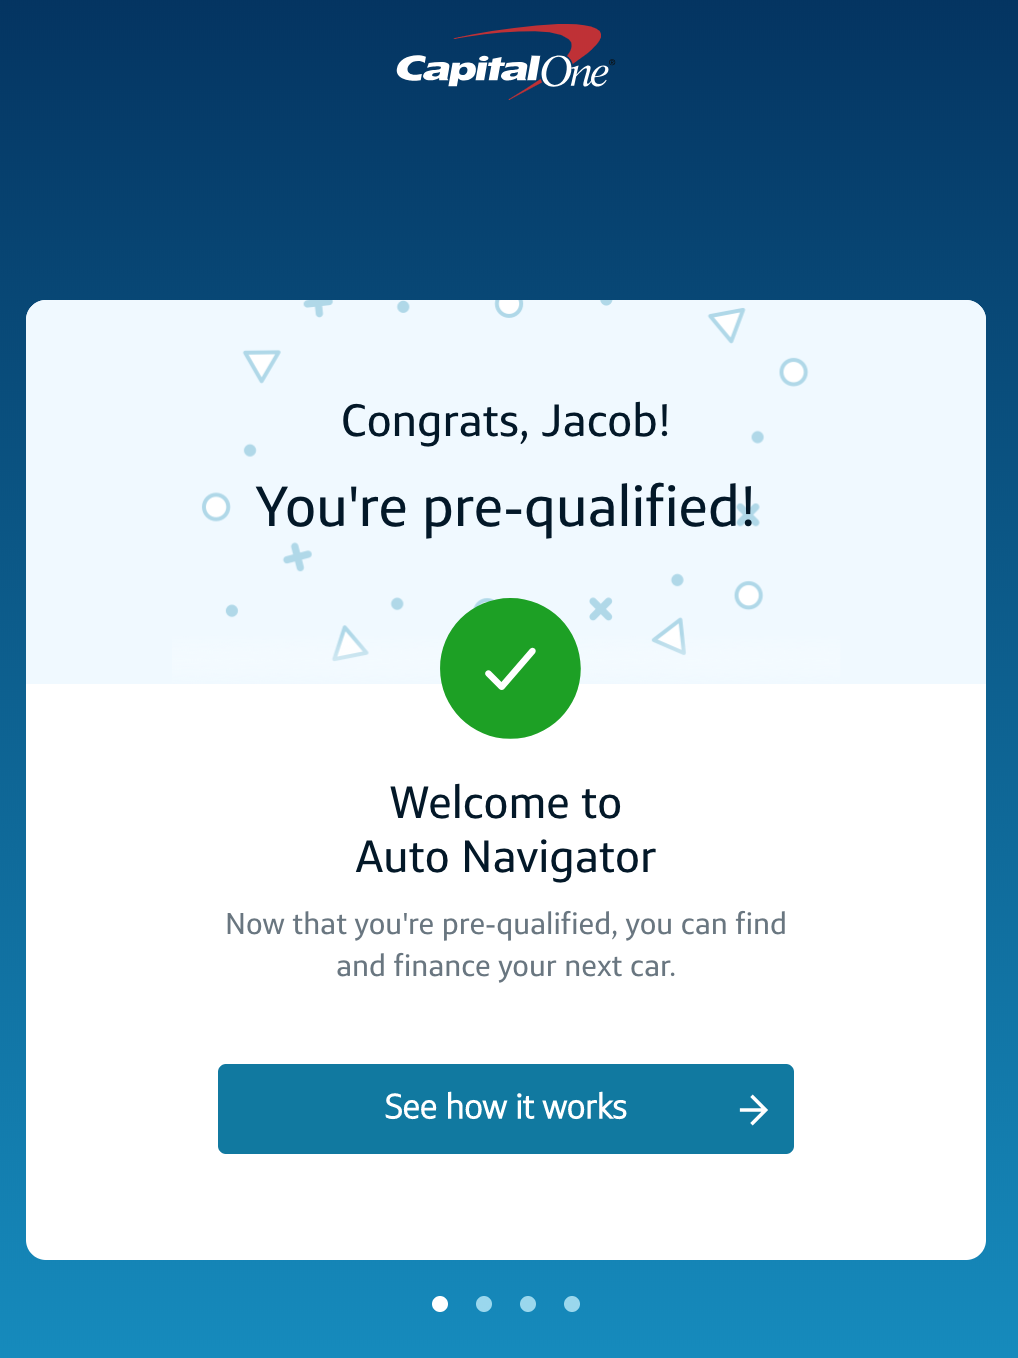
Pre‑qualification isn’t a guarantee, but it’s a useful snapshot. Capital One checks the basic elements of your credit profile—score range, existing debt, and recent payment history—using a soft inquiry that won’t dent your credit score. The result is an estimated loan amount, interest rate range, and monthly payment, all based on the information you provide.
Who’s Likely to Meet the Eligibility Bar?
There’s no one‑size‑fits‑all checklist, but most applicants share a few common traits:
- At least a 620‑plus credit score (though some borrowers with lower scores still get offers).
- Stable employment or a reliable source of income.
- A valid driver’s license and a Social Security number for identity verification.
- U.S. residency and a checking account that can be linked for payments.
Even if you fall short on one of these points, the soft pull still gives you insight without the penalty of a hard credit inquiry.
Step‑by‑Step Guide to Capital One Auto Navigator Pre‑Qualification
Ready to test the waters? Follow these five steps:
- Visit the Auto Navigator portal. The homepage prompts you to start a loan inquiry.
- Enter basic personal details. Name, address, date of birth, and the last four digits of your SSN are required.
- Provide employment and income information. You’ll need to state your employer, job title, and monthly gross income.
- Specify the vehicle you’re eyeing. You can either search the Capital One inventory or input the make, model, and year of a car you’ve found elsewhere.
- Review your pre‑qualification offer. Within minutes you’ll see an estimated APR, loan term options, and a monthly payment figure.
After you’ve received the estimate, you can either proceed directly to an online application—triggering a hard pull—or walk away and shop around with the knowledge you now have.
Why a Soft Pull Can Be a Game‑Changer
Most traditional lenders start with a hard credit inquiry, which can shave a few points off your score, especially if you’re applying to multiple lenders in a short span. Capital One’s soft‑pull approach lets you compare offers without that immediate impact, preserving your credit health for future applications such as mortgages or student loans.
Key Benefits of Using Auto Navigator for Pre‑Qualification
- Speed. The entire process takes under ten minutes on a decent internet connection.
- Transparency. You see a clear breakdown of loan terms before committing.
- Dealer integration. If you like a vehicle on the platform, you can often schedule a test drive or even complete the purchase through Capital One’s partner dealers.
- Flexibility. You can adjust the loan amount or term in the calculator to see how payments shift.
Potential Pitfalls to Keep in Mind
While the pre‑qualification tool is convenient, it isn’t flawless. The estimate assumes the information you provide is accurate; any discrepancy can lead to a different final rate. Additionally, the offers you see are based on the current market rates, which can change by the time you finalize the loan.
Another nuance: Capital One tends to favor newer vehicles, particularly those under six years old. If you’re eyeing an older car, the loan amount or interest rate might be less favorable than at a local credit union.
What Happens After You’re Pre‑Qualified?
If you decide to move forward, the next step is a formal application. This triggers a hard pull, and Capital One will verify the details you entered—employment, income, and vehicle price. Assuming everything checks out, you’ll receive a binding loan agreement, and funds are typically disbursed within a few business days.
Should the formal loan terms differ from the pre‑qualification estimate, Capital One is required to explain the reasons—often related to a more thorough credit assessment or a change in the vehicle’s price.
FAQ
Can I pre‑qualify for a loan without a Capital One checking account?
Yes. The pre‑qualification step does not require a linked checking account, though you’ll need one to set up automatic payments once the loan is funded.
Will my pre‑qualification offer expire?
Typically, the estimate is valid for 30‑45 days. After that window, the rates may be refreshed to reflect current market conditions.
Is the Auto Navigator program available in all states?
Capital One operates in most states, but a few have restrictions due to local lending laws. The portal will notify you if your state isn’t supported.
Do I have to buy a car from Capital One’s inventory?
No. You can use the pre‑qualification to finance any eligible vehicle, though using a dealer that partners with Capital One can streamline paperwork.