How Toyota OSCIOS CSC Makes Balloon Financing Easy for Your Next Car
If you’re looking for a flexible way to own the latest Toyota, Toyota OSCIOS CSC is exploring balloon finance options that let you pay a lower monthly bill while keeping future choices open. Balloon financing keeps your upfront costs down, yet it requires careful planning to avoid surprises at the end of the term. Below is a clear guide to how this strategy works, its benefits, and what you should consider before signing on the dotted line.
What Is Balloon Financing and Why It Matters
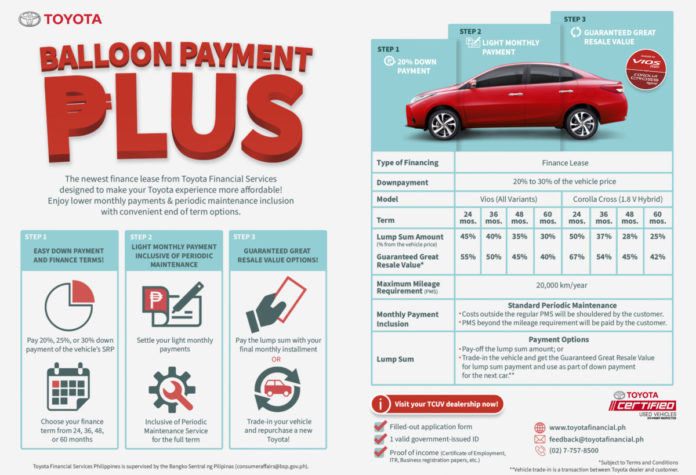
A balloon payment is a lump sum due at the end of a loan that’s smaller than a typical final payment on a fully amortized loan. Instead of paying a single amount over the full term, you spread most of the cost over several years and then pay the remaining balance in one go. This approach can be especially appealing for buyers who want to keep monthly payments low but are comfortable with a larger payment down the line—whether by selling the car, refinancing, or cashing out.
How Toyota OCSIOS CSC Tailors Balloon Plans to Your Needs
At Toyota OSCIOS CSC, the finance team offers a range of balloon loan structures. They assess credit history, vehicle depreciation, and your long‑term goals to recommend the most suitable package.
- Residual Value Flexibility: You can choose a residual value that aligns with how you expect the car’s worth to decline.
- Loan Term Options: Terms vary from three to five years, giving you control over how long the balloon payment stretches.
- Credit‑Based Rate Tiers: Better credit scores can unlock lower interest rates, reducing overall cost.
- Early‑Exit Clauses: Some plans allow you to refinance early if you anticipate a change in circumstances.
Choosing the Right Residual Value
The residual value is the estimated price of the vehicle at the end of the loan. A higher residual means lower monthly payments but a larger final payment. Conversely, a lower residual boosts monthly costs but eases the balloon burden. Discussing your expected usage, mileage, and resale plans helps set a realistic figure.
Locking in Interest Rates Early
Balloon loans often feature fixed rates for the term. Securing a rate before market fluctuations can protect you from rising interest costs. Toyota OSCIOS CSC typically offers rate locks within the first 30 days of application.
Steps to Secure a Balloon Loan at Toyota OCSIOS CSC
- Pre‑Qualification: Submit basic financial details to gauge eligibility without affecting your credit score.
- Vehicle Selection: Pick a model that suits your needs and budget; the dealer’s inventory lists depreciation estimates for each car.
- Residual & Term Negotiation: Work with a finance specialist to finalize the residual value and loan length.
- Rate Confirmation: Receive the exact interest rate and monthly payment schedule.
- Final Approval & Sign‑Off: Complete the paperwork, fund the down payment, and lock in your loan.
Pros and Cons of Balloon Financing Compared to Traditional Loans
While balloon financing can reduce monthly costs and offer flexibility, it carries risks if you’re not ready for the big payment.
- Pros:
- Lower monthly outlays.
- Potential for higher vehicle choice at the same price point.
- Opportunity to refinance or sell the car before the balloon due date.
- Cons:
- Large final payment can be a financial strain if not planned.
- Higher overall interest if the loan term is long.
- Depreciation risk if the vehicle’s market value drops below the residual.
What to Watch Out For: Hidden Pitfalls and How to Avoid Them
Even a well‑structured balloon loan can backfire if you overlook certain details.
- Excessive Down Payment: Too much cash up front can limit liquidity; balance the down payment with your overall cash flow.
- Credit Misreading: Misunderstand rate changes or early‑exit fees; review all clauses before signing.
- Insurance Coverage: Ensure your policy covers the vehicle’s full value, especially if you plan to sell before the balloon due date.
- Tax Implications: Balloon payments may affect your tax deductions; consult a tax advisor if you’re a small business owner.
Real‑World Example: A First‑Time Buyer’s Experience
Sarah, a marketing manager, needed a reliable car for her daily commute but didn't want to tie up a large lump sum. After visiting Toyota OSCIOS CSC, she chose a three‑year balloon loan with a 25 % residual value on a 2024 Camry. Her monthly payment dropped from $650 to $430. At