How UnitedHealthcare Covers Hospital Stays: A Straightforward Guide
When you’re faced with a hospital admission, the first thing on most people’s minds is how the bill will be handled. UnitedHealthcare hospital coverage can feel like a maze of terms, tiers, and exceptions, but you don’t need a degree in insurance to navigate it. This guide breaks down the essentials—what’s covered, how costs are calculated, and where you can find help—so you can focus on recovery instead of paperwork.
What Types of Hospital Services Are Typically Covered?
UnitedHealthcare’s standard plans generally include three main categories of inpatient care:
- Room and board: The cost of a semi‑private or private room, meals, and routine nursing care.
- Diagnostic and therapeutic procedures: Lab tests, imaging (like X‑rays or MRIs), surgeries, and anesthesia.
- Ancillary services: Physical therapy, pharmacy benefits, and certain medical devices prescribed during the stay.
Exact coverage varies by plan type—whether you have an individual market plan, an employer‑sponsored policy, or a Medicare Advantage option. Always verify the specifics in your Evidence of Coverage (EOC) document.
How Costs Are Calculated: Copays, Coinsurance, and Deductibles
Understanding the financial side starts with three familiar terms:
- Deductible: The amount you pay out‑of‑pocket before UnitedHealthcare begins to share costs. Some plans have separate in‑network and out‑of‑network deductibles.
- Coinsurance: After the deductible is met, you typically cover a percentage of the allowed amount—often 20% for in‑network hospital services.
- Copay: A fixed fee for certain services, such as a $150 copay for an emergency department visit.
If your plan includes a “hospital stay” benefit, the daily coinsurance may drop after a certain number of days, and some plans cap out‑of‑pocket expenses at a set maximum. Knowing these thresholds can prevent unpleasant surprises when the discharge paperwork arrives.
In‑Network vs. Out‑of‑Network: Why It Matters
UnitedHealthcare contracts with a network of hospitals, physicians, and ancillary providers. When you receive care at an in‑network facility, the insurer negotiates rates that are typically lower than what a hospital would charge an uninsured patient. Out‑of‑network care, on the other hand, can trigger higher coinsurance percentages or even balance‑billing, where the hospital bills you for the difference between its charge and the amount UnitedHealthcare reimburses.
Before an elective admission, it’s worth confirming that the hospital is in‑network. For emergency situations, most plans cover out‑of‑network care at in‑network rates, but you may still face higher cost‑sharing.
Pre‑Authorization and Its Role in Hospital Admissions
Many UnitedHealthcare plans require pre‑authorization for non‑emergency inpatient stays. The process usually involves your doctor submitting a detailed request that includes diagnosis codes, anticipated length of stay, and the procedures planned. If the request is approved, you receive an authorization number that you should keep handy at the hospital.
Skipping pre‑authorization can lead to claim denials or reduced reimbursement, which ultimately falls back on you. If you’re unsure whether a planned admission needs approval, a quick call to UnitedHealthcare’s member services line can save you headaches later.
Special Cases: Maternity, Mental Health, and Rehabilitation
Hospital coverage isn’t a one‑size‑fits‑all. For example:
- Maternity: Most plans cover labor and delivery, but they may separate the costs of a routine delivery from a C‑section, applying different coinsurance rates.
- Mental health inpatient care: Under the Mental Health Parity and Addiction Equity Act, coverage must be comparable to medical/surgical benefits, though some plans impose separate deductibles.
- Rehab and skilled nursing: After the acute stay, you might transition to a skilled nursing facility. Coverage often depends on medical necessity and may involve a different cost‑sharing structure.
Reviewing the specific language in your plan’s mental health and maternity sections helps you anticipate any additional out‑of‑pocket responsibilities.
How to Appeal a Denied Claim
Even with careful planning, you might receive a denial for a hospital charge. UnitedHealthcare’s appeal process typically follows these steps:
- Obtain the Explanation of Benefits (EOB) that explains why the claim was denied.
- Gather supporting documentation—doctor’s notes, admission records, and the original pre‑authorization if applicable.
- Submit a written appeal within the timeframe listed on the EOB (often 180 days).
- If the internal appeal fails, you can request an external review by an independent third party.
Staying organized and meeting deadlines dramatically improves the odds of a successful reversal.
Tools and Resources for Managing Your Hospital Coverage
UnitedHealthcare offers several digital tools that make tracking benefits easier:
- Member portal: Log in to view your deductible status, out‑of‑pocket maximum, and claim history.
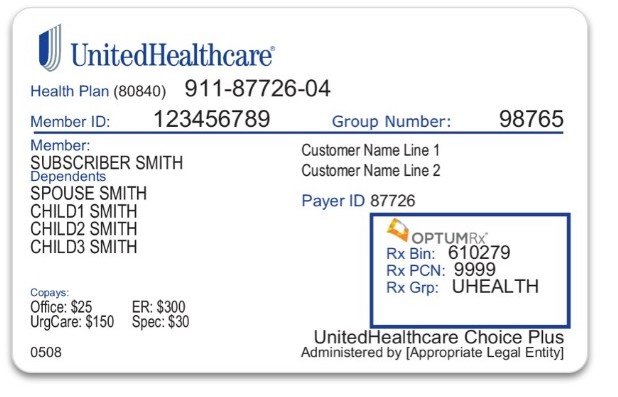
- Mobile app: Scan your insurance card, locate in‑network hospitals, and even upload documents for pre‑authorization.
- Cost estimator: Input procedure codes to get an estimate of what you’ll owe after cost‑sharing.
Using these resources before you’re admitted can give you a realistic picture of potential expenses and help you plan financially.
FAQ
What should I do if I’m admitted to an out‑of‑network hospital in an emergency?
Call UnitedHealthcare’s emergency line as soon as possible. Most plans cover emergency out‑of‑network care at in‑network rates, but you’ll still be responsible for the applicable deductible and coinsurance.
Does UnitedHealthcare cover hospital stays for outpatient surgeries?
Yes, many plans treat the observation period following an outpatient procedure as an inpatient stay for billing purposes, applying the same cost‑sharing rules as a traditional admission.
How can I find out if a specific hospital is in my plan’s network?
Use the provider search tool on the UnitedHealthcare website or app. Enter the hospital’s name or ZIP code, and the system will indicate network status and any contract variations.
Can I get a discount if I pay the hospital bill out of pocket?
Some hospitals offer self‑pay discounts, but UnitedHealthcare generally expects you to submit the claim first. If you receive a discount, you can submit the reduced amount for reimbursement, provided the plan allows it.