Mastering Delta Stock Trading: Your Ultimate Guide
When you hear the term Delta Stock Trading, you’re likely thinking about a dynamic way to gauge how sensitive an option’s price is to movements in its underlying asset. In this guide, we break down what delta really means, why it’s a game‑changer for day traders and option strategists, and how you can harness it to fine‑tune your portfolio. From basic calculations to advanced hedging, you’ll leave with a toolkit that can help you trade more confidently.
Delta Stock Trading Basics
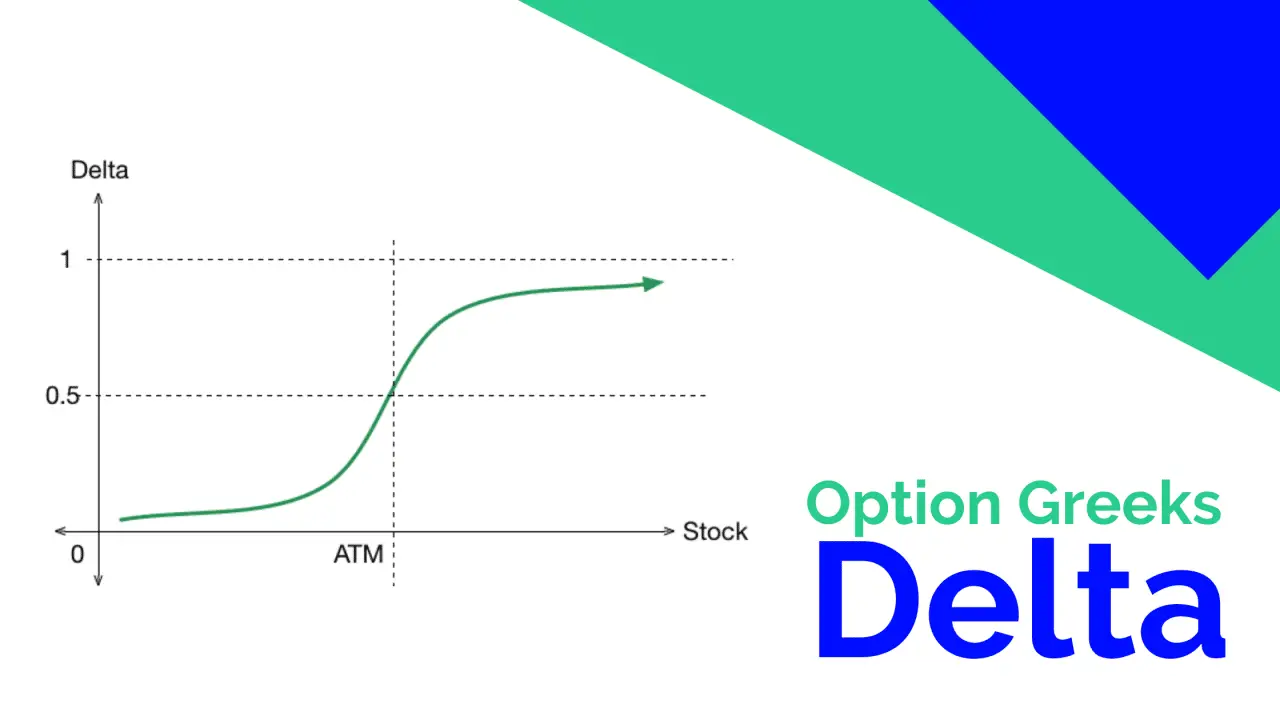
Delta is one of the “Greeks” that quantifies how a change in the price of the underlying security will affect an option’s price. Represented by the Greek letter Δ, it’s expressed as a number between 0 and 1 for call options, and between –1 and 0 for put options. For example, a delta of 0.60 means the option will move roughly $0.60 for every $1 move in the stock.
Why Delta Matters to Traders
Delta offers two primary benefits: it tells you the probability that an option will finish in-the-money and it helps you estimate how much you’ll need to adjust your position to remain neutral to price swings.
- Risk Assessment: A high delta signals a near‑in‑the‑money option, often more expensive but less volatile.
- Hedging Precision: By monitoring delta, traders can adjust the number of contracts or shares to offset potential losses.
Calculating Delta for Your Portfolio
Delta can be found on most brokerage platforms or computed using the Black–Scholes model. The basic formula is: Δ = ∂Option Price / ∂Underlying Price. In practice, you usually use the built‑in delta calculator. If you’re doing it manually:
- Identify the option’s strike price and current stock price.
- Calculate the option’s intrinsic value (difference between stock price and strike for in-the-money options).
- Divide the change in option price by the change in stock price.
Using Delta to Build Trading Strategies
Covered Calls
Sell a call option on a stock you already own. Aim for a delta of 0.30–0.40 to collect premium while limiting upside risk.
Protective Puts
Buy a put with a delta near 0.30–0.40 to shield against downside movement while keeping the cost moderate.
Delta Hedging
Adjust the number of shares or contracts so that the total delta of your position equals zero. This neutral stance protects against small price moves but still captures directional bias.
Portfolio Delta Management
Sum the deltas of all options and shares to get the portfolio’s overall delta. Rebalance regularly to keep the portfolio aligned with your risk appetite.
Tools and Platforms for Delta Tracking
Most advanced trading platforms provide real‑time delta data:
- ThinkorSwim – Interactive Brokers’ platform offers detailed Greeks.
- TradeStation – Known for customizable scripts and delta calculation.
- Delta Trading Platform – Specializes in options and futures, offering built‑in delta and gamma tools.
Common Mistakes and How to Avoid Them
- Ignoring the impact of time decay (theta) when holding options for extended periods.
- Assuming delta stays constant; it changes as the underlying price moves.
- Over‑leveraging by selling too many contracts relative to your capital base.
- Neglecting to consider gamma—the rate of change of delta—which can amplify risk in fast markets.
Advanced Concepts: Gamma, Theta, and Vega
Delta is only the tip of the iceberg. Gamma indicates how delta itself changes, theta measures time decay, and vega tracks volatility sensitivity. Understanding these Greeks together can help you design robust strategies and predict how a portfolio will behave under different market conditions.
Practical Example: Delta Hedging a Stock Position
Suppose you own 100 shares of XYZ trading at $50. You purchase one 55‑strike call with a delta of 0.25. The combined portfolio delta is 100 – 25 = 75, meaning you’re short 75 units of delta. To neutralize, buy 75 shares of XYZ. Now the portfolio delta is zero; minor price changes in XYZ won’t affect the overall value. If XYZ jumps to $55, the call becomes more valuable, but the additional shares offset the loss or gain from the stock movement.
Frequently Asked Questions
What is the difference between delta and gamma?
Delta measures how much an option’s price changes for a $1 move in the underlying. Gamma is the rate at which delta changes as the underlying price moves.
Can I use delta to predict future stock prices?
Delta offers a probabilistic insight but isn’t a forecasting tool. It tells you the likelihood of finishing in the money, not the exact price movement.
Is delta trading only for experienced option traders?
No. Many retail platforms provide delta values, and the basic concepts can be applied to simple covered call or protective put strategies.
How often should I rebalance my delta‑neutral portfolio?
Rebalance whenever the underlying price moves significantly, or at least once a week. Rapid market shifts may require more frequent adjustments.