Philippines 2023 Economic Growth: Review and Future Outlook
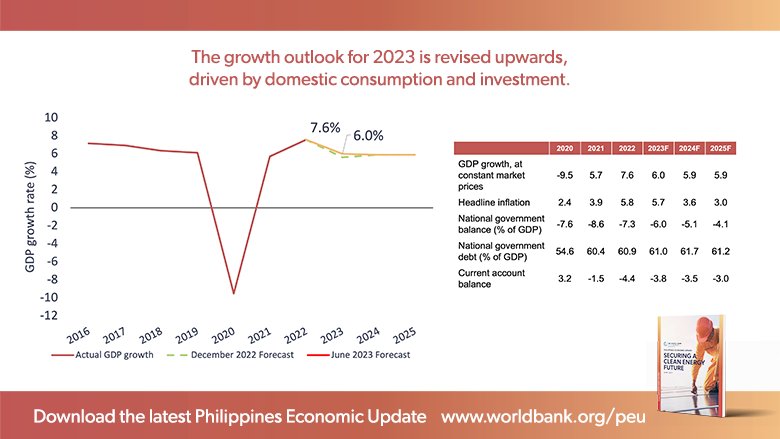
When analysts ask, “How did the Philippines fare in 2023?”, the answer is a blend of robust expansion and lingering challenges. Real GDP rose by roughly 5 percent, marking one of the faster post‑pandemic rebounds in Southeast Asia. That figure, while impressive, masks a nuanced story of sectoral shifts, policy tweaks, and external shocks that will shape the country’s trajectory in the years ahead.
2023 Growth in Numbers
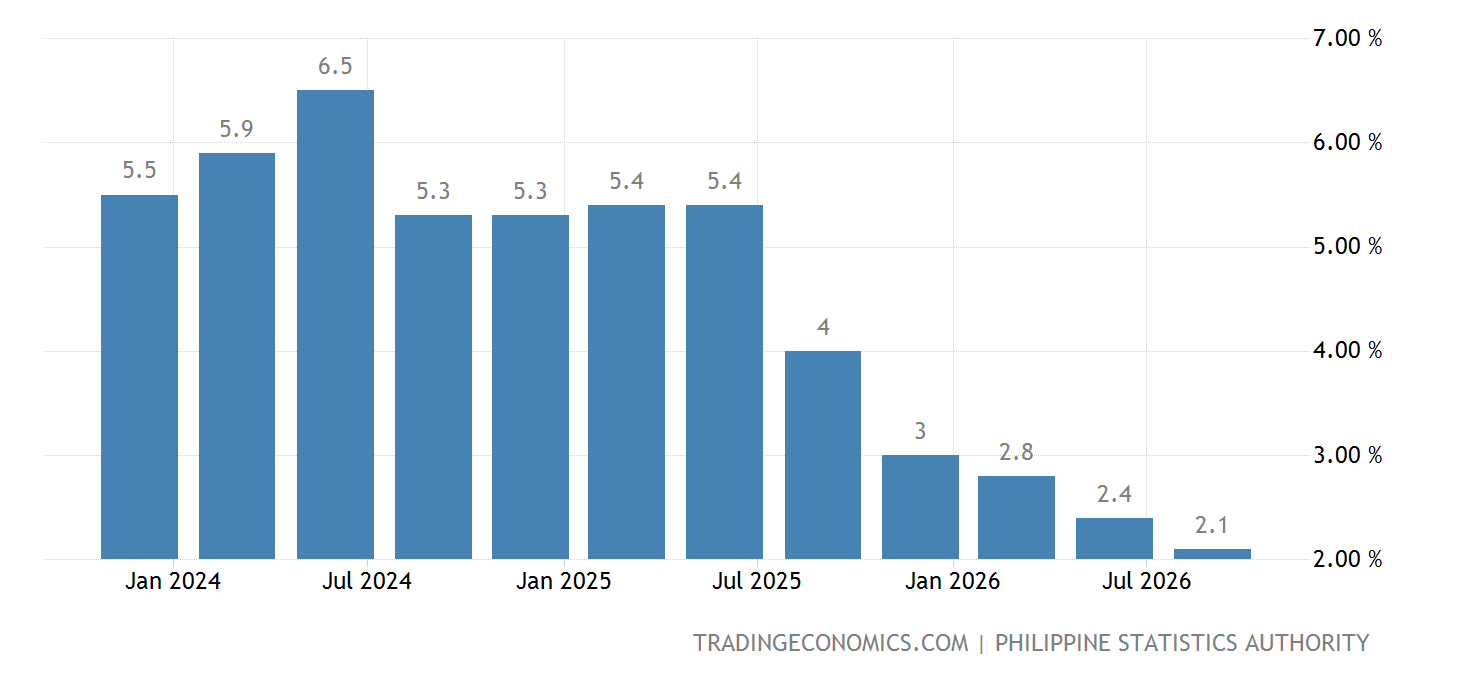
Official estimates placed the 2023 growth rate at about 5 percent, edging out the regional average of roughly 4.5 percent. Export volumes climbed, driven largely by electronics and agricultural products, while domestic consumption benefited from a gradual return to pre‑pandemic confidence. Inflation, which had peaked near 8 percent in mid‑2022, eased to the low‑4 percent range by year‑end, easing pressure on household spending.
On the fiscal front, the government narrowed its primary deficit to just under 3 percent of GDP, a modest improvement over the previous year’s 4‑percent gap. Public debt, however, remained elevated, hovering around 60 percent of GDP, underscoring the need for continued fiscal prudence.
What Powered the Expansion
Several factors converged to lift the economy. First, the service sector—especially business process outsourcing (BPO) and tourism—recovered strongly as travel restrictions lifted. BPO revenues surged, reflecting the Philippines’ reputation for English‑speaking talent and cost‑effective operations.
Second, remittances from overseas Filipino workers continued to flow robustly, providing a steady stream of foreign exchange and supporting consumption. The World Bank notes that remittances accounted for roughly 10 percent of GDP, cushioning the economy against global volatility.
Finally, a modest rebound in agricultural output helped stabilize food prices. Improved harvests of rice and corn, aided by better weather patterns and targeted government subsidies, contributed to the overall growth narrative.
Headwinds That Tempered Momentum
Despite the positive headline, the economy faced notable headwinds. Supply‑chain disruptions persisted, especially in semiconductor components essential for the electronics industry. Those bottlenecks translated into higher input costs for manufacturers, dampening profit margins.
Energy price volatility also lingered. While global oil prices moderated, the Philippines’ reliance on imported fuel kept electricity costs relatively high, pressuring both households and energy‑intensive businesses.
Moreover, the labor market showed signs of strain. While unemployment fell to around 5 percent, underemployment remained elevated, indicating that many workers were still in part‑time or informal jobs that do not fully exploit their skills.
Policy Moves That Shaped the Year
The administration rolled out a series of fiscal and monetary measures aimed at sustaining growth. The central bank, Bangko Sentral ng Pilipinas, maintained an accommodative stance, gradually easing its policy rate as inflation cooled. This helped keep borrowing costs manageable for both consumers and firms.
On the fiscal side, the government introduced tax incentives for renewable‑energy projects, signaling a shift toward greener investment. Infrastructure spending, a pillar of the “Build, Build, Build” agenda, continued but at a slower pace than initially envisioned, reflecting budget constraints and project‑implementation challenges.
Regulatory reforms targeted the ease of doing business, streamlining permit processes and improving digital government services. These steps, though incremental, were welcomed by investors seeking a more predictable operating environment.
Looking Ahead: 2024 and Beyond
Forecasts for 2024 suggest a modest slowdown, with growth expected to settle around 4.5 percent. The deceleration is largely attributed to tighter global monetary conditions and the lingering effects of supply‑chain constraints. Nonetheless, several positive forces could offset the slowdown.
First, the Philippines is poised to benefit from the broader ASEAN economic integration, which may open new markets for its export‑oriented industries. Second, continued inflows of remittances—projected to stay above 10 percent of GDP—should sustain domestic demand.
Third, the government’s focus on renewable energy and digital infrastructure could attract foreign direct investment, especially as multinational firms look for resilient supply chains in the post‑pandemic era. If these initiatives gain traction, the country could transition from rapid growth to sustainable, inclusive development.
However, achieving that transition will require tackling lingering issues: reducing public debt, improving labor‑skill matching, and bolstering climate‑resilience in agriculture and coastal communities. Policymakers who balance fiscal discipline with strategic investments will likely steer the Philippines toward a more stable growth path.
FAQ
- What was the Philippines' real GDP growth in 2023? Official data places it at roughly 5 percent, making it one of the stronger performers in the region.
- How did inflation behave in 2023? After peaking near 8 percent in 2022, inflation eased to the low‑4 percent range by the end of 2023.
- Are remittances still a key driver? Yes; they contribute about 10 percent of GDP and continue to support household consumption.
- What are the main risks for 2024? Potential risks include global monetary tightening, persistent supply‑chain disruptions, and high public debt levels.