Quick Guide to Capital One Classic Credit Card in the UK
If you’re scanning for a straightforward credit card that won’t overwhelm you with jargon, the Capital One Classic Credit Card is worth a glance. Designed for everyday spenders and those who prefer a low‑maintenance approach, this UK‑focused product promises a simple fee structure, a modest credit limit, and a brief intro‑rate period that can help you ease into credit‑building. Below, we unpack what the card actually offers, who’s likely to qualify, and how to keep it working for you without falling into common pitfalls.
What the Classic Card Offers
The Classic card positions itself as a “no‑frills” option. Its headline benefits include:
- No annual fee – you won’t be charged just for holding the card.
- A short‑term 0% interest promotion on purchases, usually lasting a few months after opening.
- Transparent, variable APR that applies once the intro period ends.
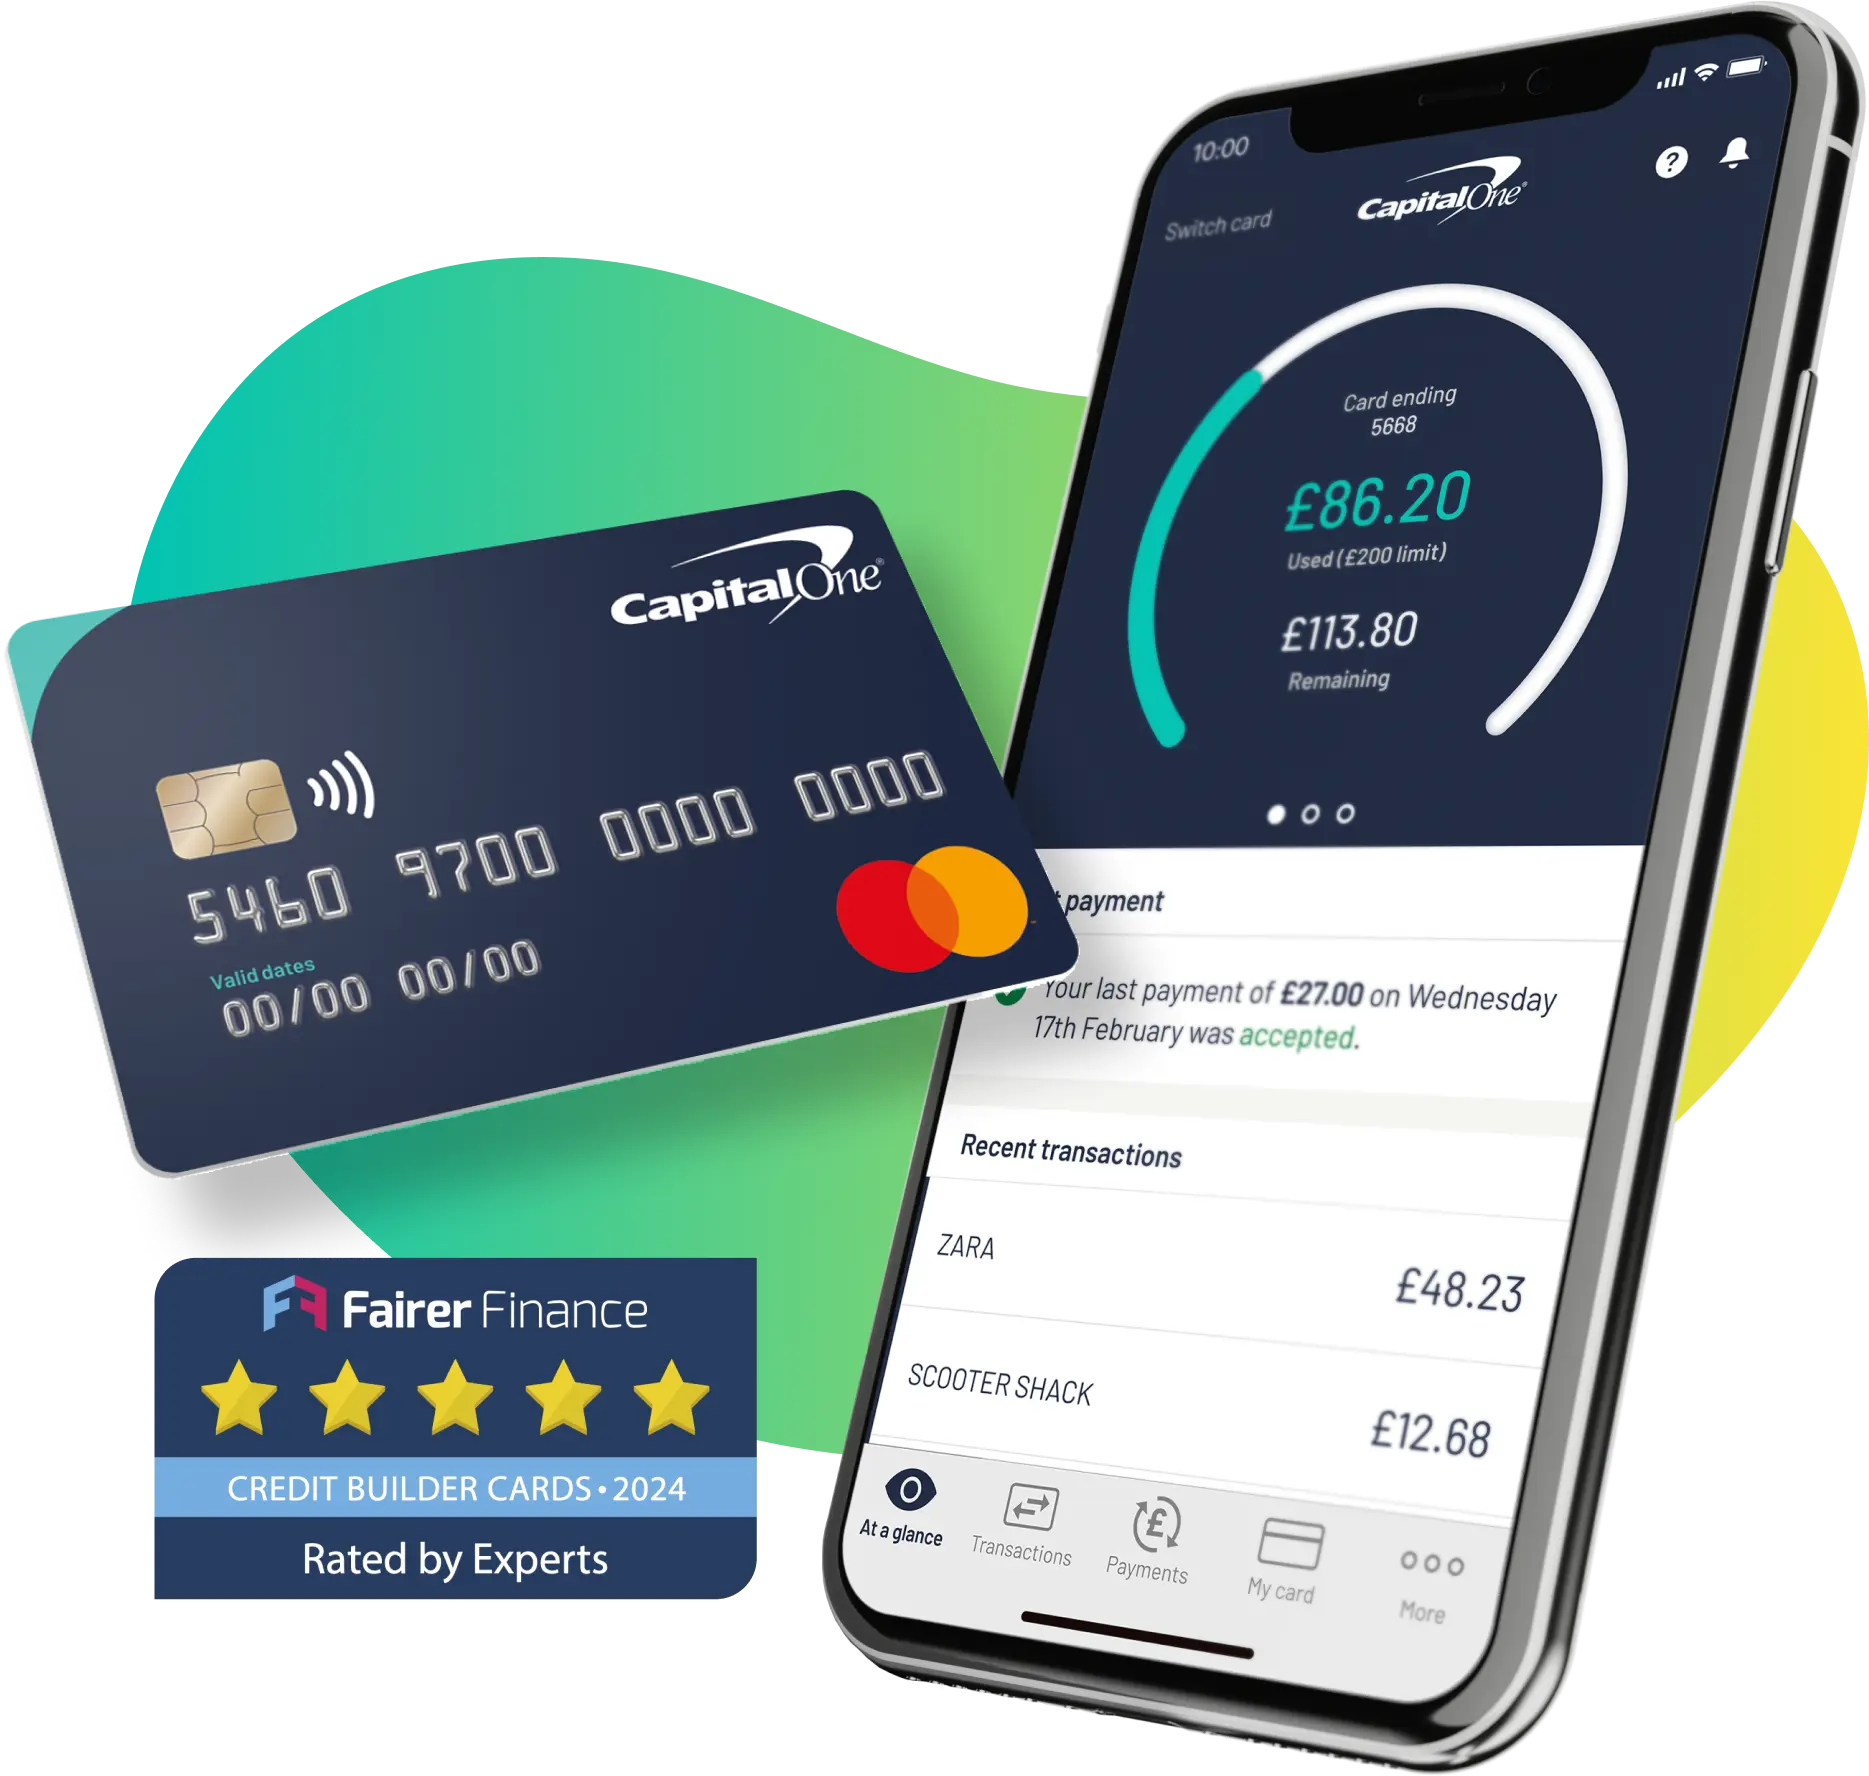
- Online account management through Capital One’s app and website.
Unlike reward‑heavy cards, there are no points or cash‑back schemes attached. That simplicity can be a relief for people who want to avoid tracking bonus categories while still enjoying the convenience of a plastic payment method.
Eligibility and Application Process
Capital One runs a soft credit check during the initial application stage, which means you can see whether you’re likely to be approved without hurting your credit score. If you pass this gate, a hard inquiry will follow once you submit the formal request.
Typical eligibility criteria include:
- Being at least 18 years old.
- Having a UK residential address and a valid UK bank account.
- Demonstrating a reasonable credit history – often a minimum of six months of credit activity, though exceptions exist for those rebuilding after a short lapse.
The online form takes just a few minutes: you’ll need your National Insurance number, proof of address, and details of any existing credit commitments. Approval can be instantaneous, but in some cases Capital One may request additional documentation.
Fees, Interest, and Charges
Beyond the absence of an annual fee, the most common costs to watch are:
- Late payment fee – typically a flat rate charged if you miss a due date.
- Foreign transaction fee – a percentage of any spend made in a currency other than GBP.
- Cash advance APR – usually higher than the purchase rate and without an intro‑free period.
The variable APR for purchases after the introductory phase often sits in the mid‑teens, but the exact figure depends on your credit profile and the Bank of England base rate. As a rule of thumb, paying the full balance each month eliminates interest entirely.
How to Use the Card Responsibly
Even a simple card can become a financial stressor if mismanaged. Here are a few practical habits:
- Set up automatic payments for at least the minimum amount to avoid late fees.
- Keep utilisation below 30% of your credit limit; this helps maintain a healthy credit score.
- Take advantage of the 0% intro period by consolidating short‑term purchases you can pay off before the rate kicks in.
- Review the monthly statement online and flag any unfamiliar charges promptly.
Because the card doesn’t reward spending, there’s little incentive to overspend just to chase points. Treat it as a tool for regular, necessary purchases rather than a source of extra cash flow.
Comparison with Other UK Credit Cards
When you line the Classic up against more feature‑rich cards, a few contrasts emerge:
- Rewards cards (e.g., Tesco Bank Clubcard) offer points but often carry an annual fee and higher APRs.
- Balance‑transfer cards may provide longer 0% periods on existing debt but usually require a decent credit score to qualify.
- Premium travel cards deliver lounge access and travel insurance, yet they tend to be pricey and target frequent flyers.
If your priority is a clean, low‑cost card for everyday use, the Classic holds its own. It shines for people who are new to credit, rebuilding after a setback, or simply don’t want to juggle multiple reward schemes.
Common Questions
Do I need a good credit score to get the Classic card?
A stellar score isn’t mandatory, but a reasonable credit history improves your odds. Capital One’s soft check helps you gauge eligibility before the hard inquiry.
Are there any hidden charges I should be aware of?
The main fees are the late payment penalty, foreign transaction fee, and cash‑advance interest. All are disclosed up front in the terms and conditions, so there are no surprise surcharges.
Can I increase my credit limit over time?
Yes. Capital One periodically reviews account activity. Consistently paying off balances and keeping utilisation low can trigger an automatic limit raise.
What happens if I miss a payment?
A missed payment incurs a late fee and may raise your APR. It also signals a negative mark to credit reference agencies, potentially affecting future applications.