Telegraphic Transfer Payments Explained: A Simple Guide
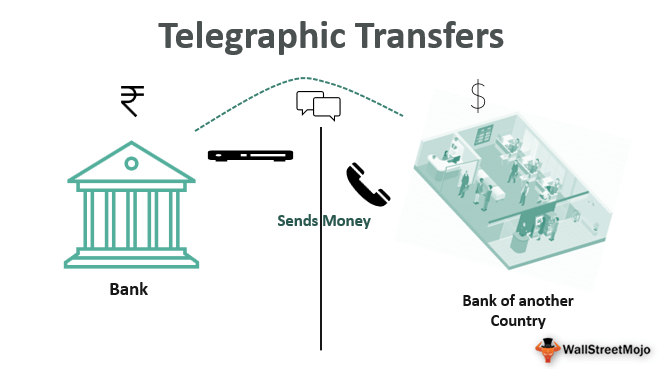
When you need to move money across borders quickly, telegraphic transfer payments (also called wire transfers) are the go-to option. These electronic transfers bypass paper checks and use secure networks to move funds from one bank to another, often in just a few hours. If you’re new to the world of international banking, understanding the mechanics of a telegraphic transfer can feel daunting. This guide breaks everything down into clear, step‑by‑step explanations so you can navigate the process with confidence.
What Is a Telegraphic Transfer?
Originally derived from telegraphy, the term now refers to the electronic transmission of payment instructions between banks. Unlike traditional checks, a telegraphic transfer is recorded instantly in the sender’s and recipient’s accounts. Banks use the SWIFT network—a global messaging system—to exchange the necessary details. Because the information travels digitally, the transfer can be completed 24/7, making it ideal for time‑sensitive business or personal transactions.
How Telegraphic Transfer Payments Work
The core of a telegraphic transfer is the exchange of a standardized message that includes all the data a bank needs to move the money. The sender’s bank creates this message and pushes it through the SWIFT network to the recipient’s bank. Once the recipient bank receives the message, it credits the beneficiary’s account. The whole chain—from initiation to settlement—can take anywhere from a few minutes to a couple of business days, depending on the banks and countries involved.
Key Information Needed
Before you start a transfer, gather the following:
- Beneficiary’s full name and address
- Beneficiary’s account number or IBAN (International Bank Account Number)
- Bank’s SWIFT/BIC code
- Bank’s full name and branch address
- Purpose of the transfer (optional but often required for compliance)
Missing or incorrect details can lead to delays or even returned payments, so double‑check each field.
The Transfer Process
1. Initiation: You provide the above details to your bank, either online or at a branch. Some banks allow you to schedule future dates.
2. Processing: The bank verifies the sender’s identity and available funds. It then drafts the SWIFT message and forwards it to the recipient’s bank.
3. Settlement: The recipient bank debits the sender’s account via the correspondent bank and credits the beneficiary. If currencies differ, an exchange rate is applied.
4. Confirmation: You receive a transfer reference number and can track the status through your bank’s portal.
Benefits and Limitations
Telegraphic transfer payments offer several advantages:
- Speed—most transfers settle within 24 hours.
- Global reach—any bank with SWIFT access can receive the funds.
- Security—messages are encrypted and verified by banks.
However, there are drawbacks to keep in mind:
- Higher fees than local transfers, especially for currency conversions.
- Potential exchange rate spread that can reduce the final amount.
- Risk of fraud if you provide details to a malicious third party.
Common Mistakes to Avoid
1. Entering the wrong account number—even a single digit error can misdirect funds.
2. Using the wrong SWIFT code—each branch has its own code; using a generic one can route the payment incorrectly.
3. Ignoring transfer limits—some banks cap daily or weekly transfer amounts; exceeding this can trigger a hold.
4. Failing to keep the reference number—if the transfer is delayed, you’ll need it to trace the payment.
Tips for a Smooth Transaction
- Verify all details before submitting. Ask the recipient to confirm their bank’s SWIFT code and account number.
- Use secure channels—never share your bank login or transfer details via email or unsecured messaging.
- Keep a receipt—most banks issue a transfer confirmation with a reference number.
- Monitor the status—most banks provide real‑time updates; if the transfer sits pending for more than 48 hours, contact customer service.
- Consider timing—sending on weekends or holidays can delay processing until the next business day.
Frequently Asked Questions
What is the difference between a telegraphic transfer and a regular wire transfer?
In everyday language they’re often used interchangeably. Technically, a telegraphic transfer is the specific SWIFT message used to send funds, while a wire transfer can refer to any electronic bank-to-bank payment.
Can I track a telegraphic transfer in real time?
Most banks offer an online portal or mobile app where you can see the transfer status. You’ll need the reference number that the bank provides when you initiate the payment.
What happens if I give incorrect beneficiary details?
The transfer may be returned to your account, or worse, credited to the wrong person. In that case, you’ll need to work with both banks to reverse the transaction—a process that can take several days.
Are there lower‑fee alternatives for international transfers?
Some fintech services use peer‑to‑peer networks to offer lower fees and competitive exchange rates. However, they may lack the regulatory safeguards of traditional banks, so assess your risk tolerance before switching.