Visa vs. PayPal: Which Stock Offers Better Long‑Term Value?
Why the Comparison Matters for Investors
When you hear “Visa” and “PayPal” in the same breath, the first thought is usually “digital payments.” Yet the two companies sit on opposite sides of the financial ecosystem. Visa operates a global network that moves billions of card transactions each day, while PayPal provides a consumer‑focused platform for online and mobile payments. For a portfolio that leans on fintech, weighing their stock prospects side by side is more than a curiosity—it’s a strategic decision that can shape returns for years to come.
Business Models in a Nutshell
Visa earns most of its money by charging fees to banks and merchants for using its network. Those fees are largely transaction‑based, meaning revenue scales automatically as the volume of card purchases rises. The company doesn’t issue cards itself, which shields it from credit‑risk losses.
PayPal runs a more diversified platform. It collects merchant fees on each transaction, but also generates income from value‑added services such as PayPal Credit, Braintree (its white‑label processing arm), and the growing suite of crypto‑related offerings. Because PayPal owns the user relationship, it can cross‑sell products, but it also bears more direct competition from other e‑wallets and from the banks that partner with Visa.
Financial Performance at a Glance
Both firms posted solid top‑line growth in 2023. Visa reported net revenue of roughly $29.3 billion, up about 12 % from the prior year, driven by a rebound in cross‑border spending. PayPal’s revenue hovered near $27.5 billion, reflecting a modest 7 % increase, helped by higher transaction volumes but offset by slower growth in its core checkout segment.
- Operating margins: Visa consistently hovers above 55 %, while PayPal’s margins sit in the low‑40 % range.
- Free cash flow: Visa generated over $15 billion, giving it ample room for share buybacks and dividend hikes; PayPal’s free cash flow was more modest, around $2 billion, reflecting heavier reinvestment in technology.
- Balance sheets: Visa’s debt‑to‑equity ratio is under 0.4, signaling a very strong capital position. PayPal carries more leverage, though still within a manageable range for a tech‑oriented firm.
Growth Drivers and Headwinds
Visa’s future hinges on the continued shift to electronic payments worldwide. Emerging markets, where cash still dominates, present a sizable runway. Additionally, Visa’s investments in tokenization and real‑time payments (e.g., Visa Direct) could unlock new fee streams.
PayPal’s upside is tied to its ability to expand beyond simple checkout. The acquisition of Honey and the push into “buy now, pay later” (BNPL) services illustrate a strategy to capture more of a shopper’s wallet. However, PayPal faces regulatory scrutiny over its crypto initiatives and intense competition from Apple Pay, Google Wallet, and traditional banks that are rolling out their own digital wallets.
Valuation: How the Market Prices the Two
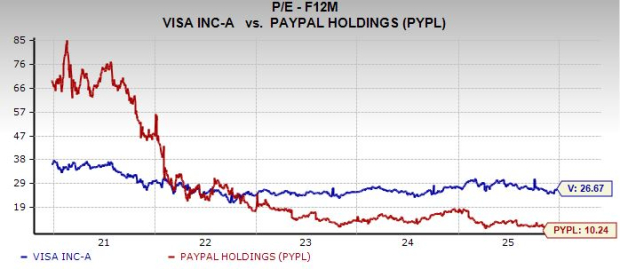
As of the latest close, Visa trades at a price‑to‑earnings (P/E) multiple near 30×, reflecting investor confidence in its stable, high‑margin cash flow. PayPal’s P/E sits around 20×, which may appear cheaper but also signals the market’s caution about its growth consistency and higher operational costs.
Dividend yield is another differentiator. Visa pays a modest dividend that has risen for 12 consecutive years, appealing to income‑focused investors. PayPal does not currently pay a dividend, choosing instead to reinvest earnings into product development and acquisitions.
What the Numbers Mean for a Portfolio
If you prioritize defensive exposure with a reliable dividend, Visa’s high‑margin, low‑volatility profile fits well in a core holdings bucket. Its global brand and entrenched network make it a relatively safe play, especially during economic downturns when consumers still need to pay for essentials.
Conversely, if you’re comfortable with a higher risk‑return trade‑off and want exposure to the broader fintech narrative, PayPal offers upside potential. Its ability to innovate—whether through BNPL, crypto, or expanding merchant services—means the stock could outpace Visa if those bets pay off, but the upside comes with greater earnings volatility.
Investor Checklist
- Assess your risk tolerance: Visa = low‑to‑moderate risk; PayPal = higher risk with upside.
- Consider dividend needs: Visa provides a growing yield; PayPal does not.
- Look at growth horizons: Visa’s long‑term tail is global card adoption; PayPal’s is platform diversification.
- Watch regulatory developments: Both face scrutiny, but PayPal’s crypto and BNPL ventures attract more attention.
Frequently Asked Questions
Q: Which stock has performed better over the past five years?
A: Visa has generally delivered a steadier total return, thanks to its consistent earnings growth and dividend increases. PayPal’s performance has been more cyclical, with periods of strong gains offset by pullbacks after earnings misses.
Q: Should I hold both stocks for diversification?
A: Many investors find value in allocating to both. Visa offers stability and cash flow, while PayPal adds exposure to the fast‑moving digital‑payments space. Balancing the two can smooth portfolio volatility.
Q: How do macroeconomic trends affect these companies?
A: Visa’s earnings are closely linked to consumer spending and travel, which can dip in recessions but tend to rebound quickly. PayPal’s revenue is more sensitive to e‑commerce activity and discretionary online purchases, making it slightly more vulnerable to economic slowdowns.
Q: Is the current valuation for either stock overpriced?
A: Valuation is subjective, but Visa’s premium P/E reflects its strong cash flow and dividend track record. PayPal’s lower multiple suggests the market is pricing in execution risk. Investors should weigh these factors against their own growth expectations.