What Happens When Iican AC Corp Owns an LLC: A Complete Guide
When Iican AC Corp decides to own an LLC, the move isn’t just a legal formality—it reshapes liability, tax treatment, and operational flexibility. Many businesses wonder whether a corporation can hold an LLC and what that structure really means. Below we unpack the key reasons behind the decision, the mechanics of setting it up, and the common pitfalls to watch out for.
Why a Corporation Might Form an LLC
Corporations often spin off an LLC to isolate a specific project or asset. By housing a high‑risk venture in an LLC, the parent corporation shields its broader balance sheet from potential lawsuits. This segregation is especially useful for real‑estate holdings, joint ventures, or experimental product lines where uncertainty is high.
Another driver is flexibility. LLCs allow for customized profit‑sharing arrangements among members, which can be harder to achieve under strict corporate bylaws. When Iican AC Corp wants to bring in outside investors for a single venture, an LLC can accommodate varied ownership stakes without diluting the corporation’s stock.
Legal Structure and Liability Implications
Legally, an LLC is a separate entity, even if a corporation owns 100 % of its membership interests. This separation means creditors of the LLC typically cannot reach the corporation’s assets, and vice‑versa, provided corporate formalities are observed. However, courts may “pierce the veil” if the LLC is merely an alter‑ego of the corporation—such as when finances are commingled or the LLC lacks its own governance.
To preserve that liability shield, Iican AC Corp should maintain distinct bank accounts, hold separate meetings, and keep thorough records for the LLC. Treating the LLC as a bona fide subsidiary, rather than a bookkeeping convenience, is essential for protecting both entities.
Tax Considerations for Corporate‑Owned LLCs
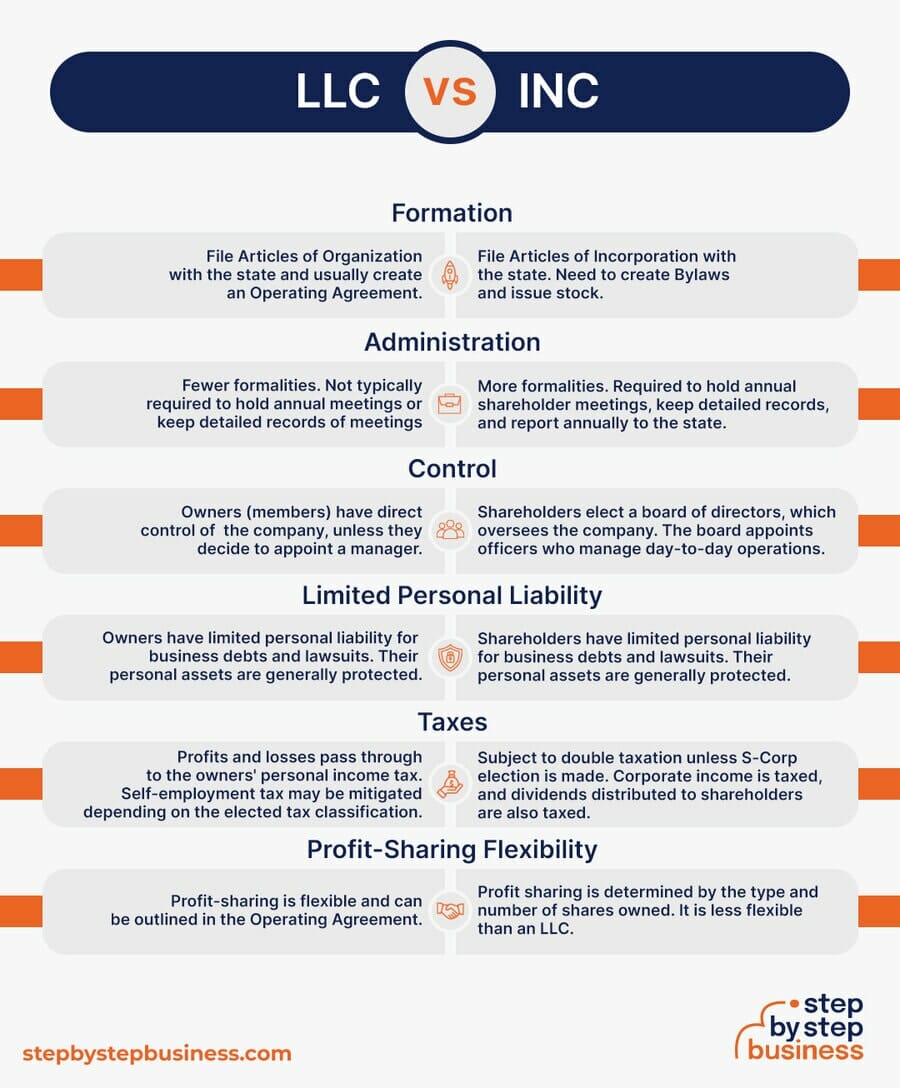
By default, a single‑member LLC owned by a corporation is treated as a disregarded entity for federal tax purposes. That means the LLC’s income, deductions, and credits flow directly onto the corporation’s tax return (Form 1120). The benefit? Simpler filing—no separate partnership or S‑corp election is required.
Yet there are scenarios where electing corporate tax treatment for the LLC (by filing Form 8832) makes sense, especially if the LLC expects to retain earnings or if the corporation wants to take advantage of certain deductions unavailable to pass‑through entities. Consulting a tax professional ensures the election aligns with overall tax strategy.
Steps to Set Up an LLC Under Iican AC Corp
First, choose a unique name that complies with state naming rules and clearly distinguishes the LLC from Iican AC Corp. A simple “Iican AC LLC” often works, but you must check the Secretary of State’s database for availability.
Next, file Articles of Organization with the appropriate state agency, typically the Secretary of State. The filing includes the LLC’s name, registered agent, and the corporation’s name as the sole member. Fees vary by state, ranging from $50 to $200.
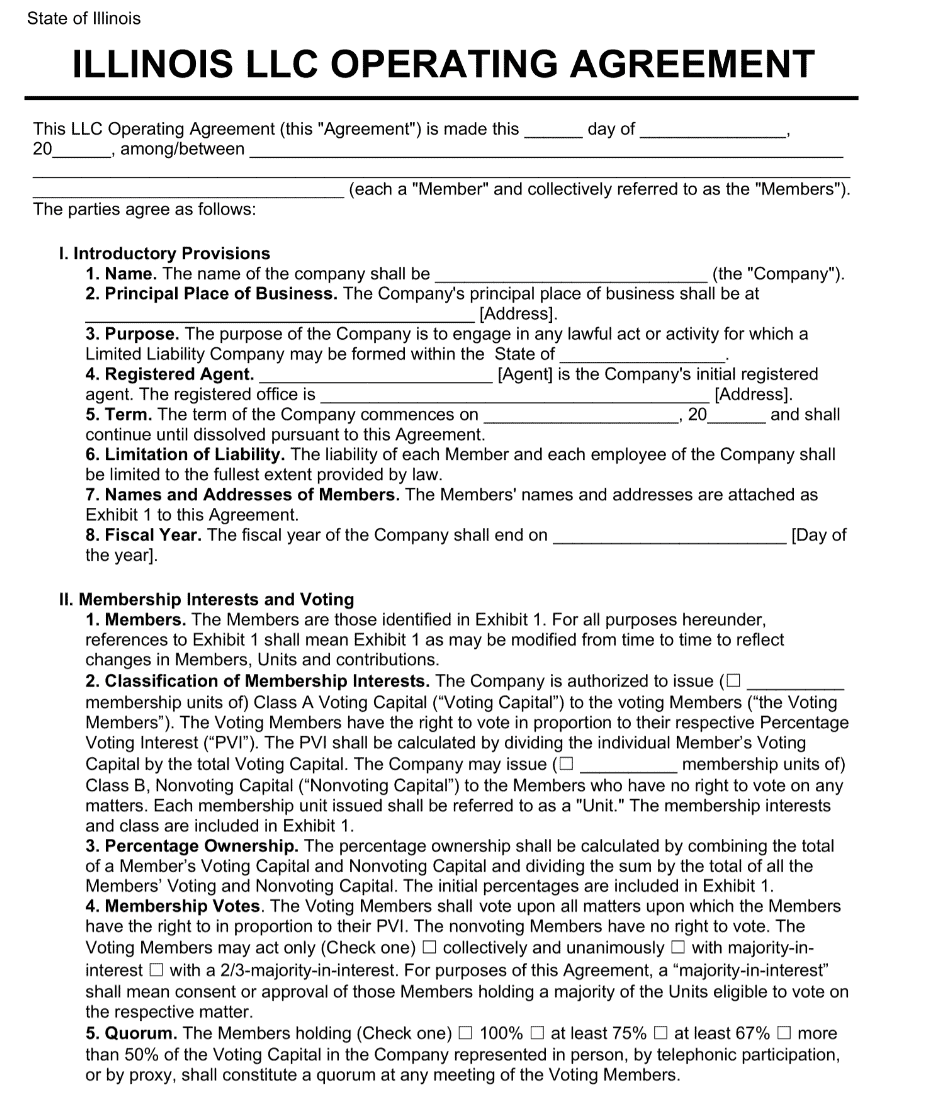
After formation, draft an operating agreement that outlines the corporation’s rights, profit allocation, and management structure. Even though a single member can operate without a formal agreement in many states, having one on file helps demonstrate the LLC’s independence if legal challenges arise.
Finally, obtain any necessary business licenses, register for state taxes, and set up a dedicated bank account. Remember to file any required annual reports to keep the LLC in good standing.
Managing the Relationship Between Corp and LLC
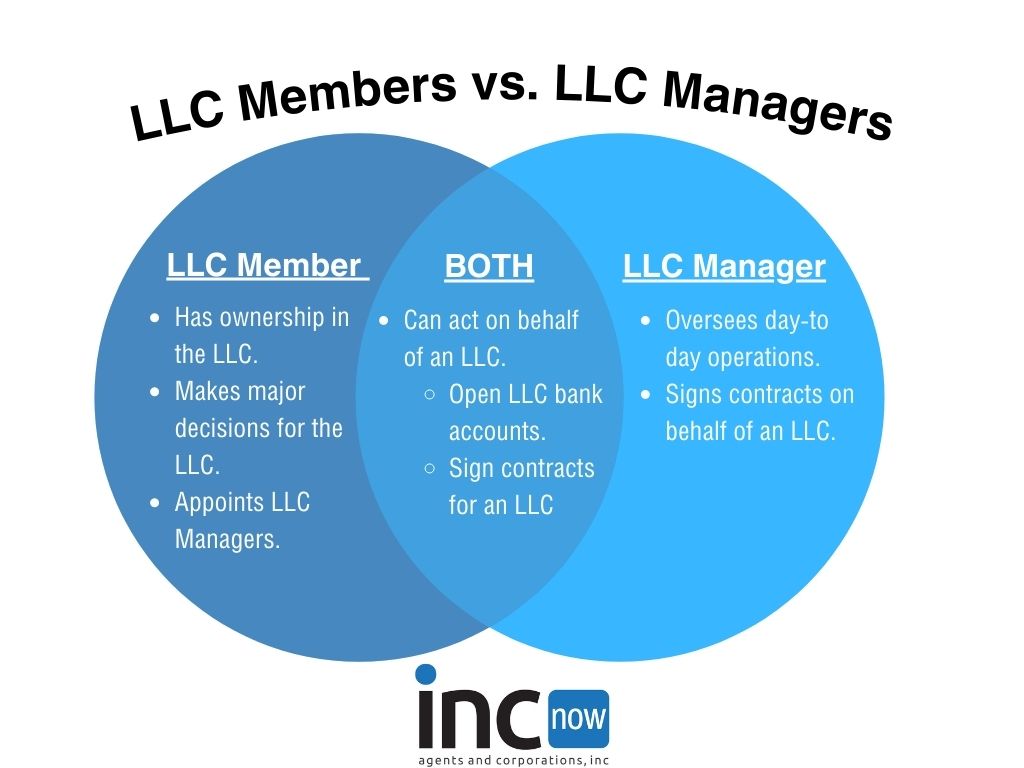
Although the corporation holds 100 % of the LLC, it’s wise to appoint a separate manager or managing member for day‑to‑day operations. This separation reinforces the LLC’s distinct identity and prevents the “alter‑ego” argument that could jeopardize liability protection.
Financially, the corporation should treat any capital contributions to the LLC as equity, not as a loan, unless a formal debt instrument is created. Proper documentation of these contributions avoids confusion during audits or when the LLC seeks external financing.
Potential Pitfalls and Best Practices
One common mistake is neglecting state‑specific compliance. Some states require an annual franchise tax or a minimum capital contribution for LLCs owned by corporations. Failing to meet these obligations can lead to penalties or administrative dissolution.
Another risk involves the “double‑tax” misconception. Because the LLC’s income is passed through to the corporation, the corporation pays tax at the corporate rate, but there is no additional tax at the LLC level. However, if the corporation later distributes profits to shareholders, those dividends may be taxed again at the individual level.
Best practice: conduct a periodic “entity health check.” Review the LLC’s operating agreement, verify that all corporate formalities are observed, and confirm that the LLC’s activities remain within the scope intended by Iican AC Corp. Regular audits help catch inadvertent commingling early.
When to Seek Professional Guidance
Because corporate and LLC law intersect with tax, securities, and employment regulations, it’s rarely a one‑size‑fits‑all decision. Engaging a corporate attorney familiar with the jurisdiction where the LLC will operate can save headaches down the line. Likewise, a CPA or tax advisor can model different tax outcomes to determine whether a disregarded entity or a corporate‑taxed LLC better serves Iican AC Corp’s strategic goals.
FAQ
- Can Iican AC Corp own multiple LLCs? Yes. A corporation can be the sole member of several LLCs, each used to compartmentalize risk or manage distinct business lines.
- Do shareholders of Iican AC Corp have any direct interest in the LLC? Not directly. Their interest lies in the corporation’s share value, which reflects the LLC’s performance as part of the corporation’s consolidated earnings.
- What happens if the LLC incurs a loss? The loss flows through to Iican AC Corp’s tax return, potentially offsetting other corporate income, subject to applicable tax rules and limitations.
- Is it necessary to register the LLC in the same state as the corporation? No. The LLC can be formed in any state, though choosing a state with favorable LLC laws (like Delaware or Nevada) may provide additional benefits.