What Real Users Say About Klarna’s Invoice Payment
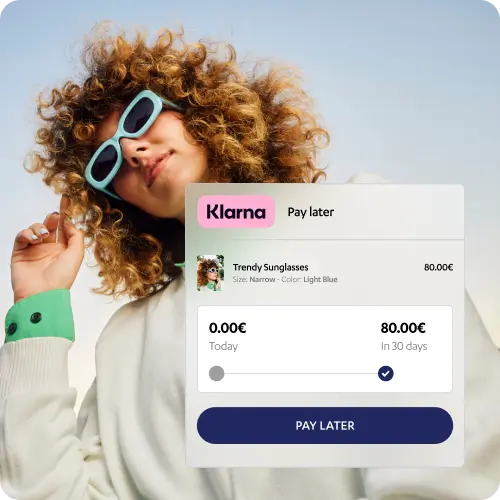
When you click “Buy now, pay later” on a shopping site, the option that often feels most like traditional credit is Klarna’s invoice payment. Instead of a monthly instalment plan, you receive a single invoice that you can settle within a short grace period—usually 14 or 30 days. This model promises flexibility without the hassle of a revolving balance, but how does it play out in everyday life? Below, I share the practical insights I’ve gathered from my own usage and from conversations with other shoppers.
How Klarna’s Invoice Payment Works
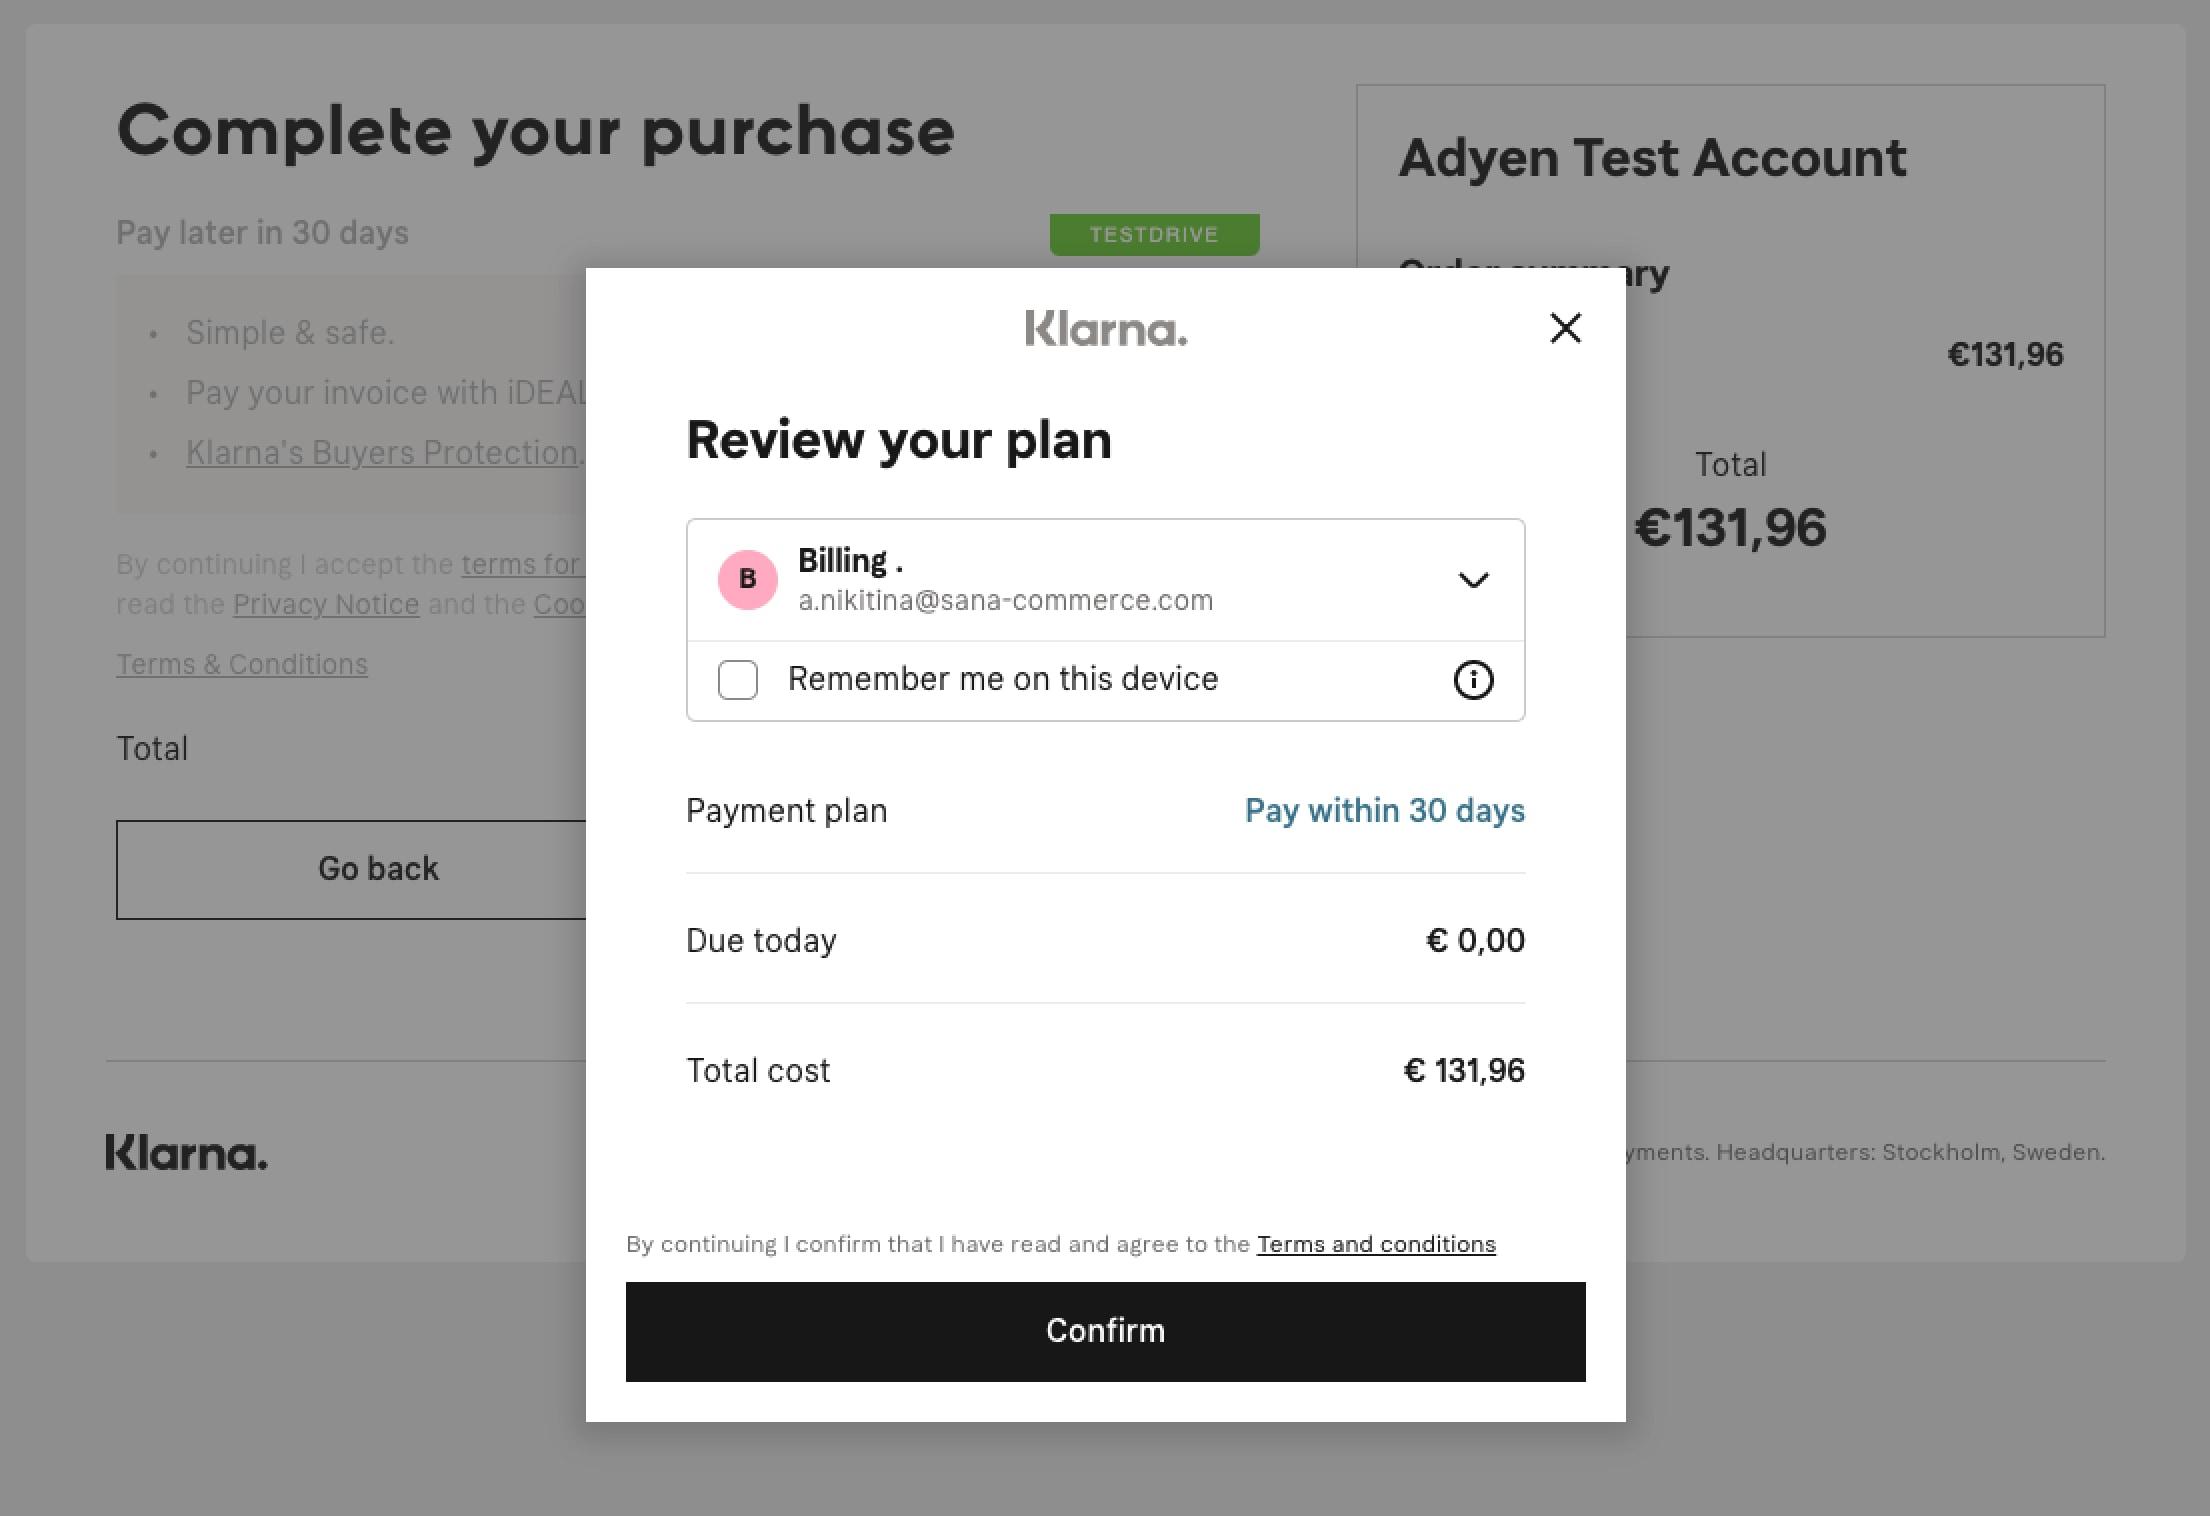
First, you select the invoice method at checkout. Klarna then runs a quick soft credit check—no hard pull, so it won’t affect your credit score. If approved, you’ll receive an electronic invoice by email, complete with a due date and a secure link to pay. Payments can be made via bank transfer, credit/debit card, or even directly from a linked bank account, depending on what the merchant supports. The key point is that you only owe the amount once; there are no hidden instalments lurking behind the scenes.
Because the bill is due in full, Klarna typically adds a modest late‑fee if you miss the deadline. Otherwise, you avoid interest altogether, which is why many treat it as a short‑term, interest‑free loan. The whole process is designed to be seamless—click, receive, pay—mirroring the simplicity of a digital receipt.
Real‑World Experiences: What Customers Notice
After trying the service for several months, a few patterns emerged that seem common among users:
- Convenient for one‑off purchases. Shoppers love the ability to order a pricey item—like a new laptop or a designer dress—and defer payment until they’ve received it.
- Clear communication. The invoice email is usually well‑formatted, with a bold due date and a QR code for quick mobile payment.
- Occasional delays. A small number of users report that the invoice arrives later than expected, especially during holiday spikes, which can compress the effective repayment window.
- Impact on budgeting. Because the amount appears as a single line item in your bank statements, it’s easier to track than multiple instalments, but it does require you to set aside the full sum ahead of the due date.
Pros and Cons From a User’s Viewpoint
Pros: The most celebrated advantage is the interest‑free grace period. For people who can pay the balance within two weeks, it’s essentially a free loan. Additionally, the soft credit check means you can try the service without jeopardising your credit report.
Cons: The model hinges on timely payment. Miss a deadline and you’ll face a late‑fee that can be as high as €15‑€25, depending on the market. Some users also mention that the merchant’s return policy sometimes conflicts with Klarna’s own dispute process, leading to a bit of back‑and‑forth if you need a refund.
Tips to Make the Most of the Service
Here are a few practical suggestions that have helped me avoid pitfalls and maximise the benefit of Klarna’s invoice payment:
- Set a calendar reminder for the due date, preferably a day or two before the deadline.
- Keep a small “buffer” fund in a separate savings account; that way you’re not scrambling for cash if the invoice lands later than expected.
- Check the merchant’s return policy before you buy. If a return is likely, make sure you understand how Klarna will handle the refund—some merchants issue a new invoice rather than reversing the original.
- Use the mobile app’s push notification feature. It alerts you when the invoice is generated and when payment is due, reducing the risk of oversight.
Frequently Asked Questions
- Can I use Klarna’s invoice payment for any online store? Most major retailers that partner with Klarna support the invoice option, but it’s always listed alongside other Klarna methods at checkout.
- What happens if I can’t pay the invoice on time? Klarna will charge a late‑fee and may restrict future use of the invoice service until the balance is settled.
- Is there a credit limit for the invoice payment? Yes, Klarna assigns a personal spending limit based on your purchase history and the soft credit check. The limit can increase over time as you demonstrate reliable payments.
- Will using the invoice affect my credit score? The soft check used for approval does not impact your credit score. However, repeated late payments could be reported to credit bureaus, so punctuality is key.