How Islamic Madhhab Shape Mainstream Islamic Economics
When scholars talk about Islamic economics, the discussion often drifts toward concepts like riba, zakat, and profit‑and‑loss sharing. Yet a less visible but equally crucial factor is the role of madhhab in mainstream Islamic economics. These legal schools—Hanafi, Shafi'i, Maliki, and Hanbali—provide the jurisprudential scaffolding that determines how theory becomes practice. Understanding their influence helps anyone navigating contemporary Islamic finance, policy formulation, or academic research.
Why Legal Schools Matter in Economic Thought
The four Sunni madhhab are not merely historical curiosities; each offers a distinct methodology for interpreting the Qur’an and Sunnah. That methodology extends to economic matters, shaping everything from contract design to the permissibility of modern financial instruments. For instance, the Hanafi school’s flexible approach to “custom” (ʿurf) often permits innovative leasing structures, while the Maliki emphasis on public interest (maslaha) can lead to stricter scrutiny of speculative activities.
Because most Muslim‑majority economies operate under a mix of civil law and Sharia‑based regulations, policymakers routinely consult the madhhab to reconcile national legislation with religious obligations. The result is a patchwork of rules that, while diverse, shares a common commitment to justice, equity, and the avoidance of exploitation.
Key Madhhab Perspectives on Core Economic Issues
Each school tackles the foundational pillars of Islamic economics in its own way. Below is a brief snapshot of where they converge and where they diverge.
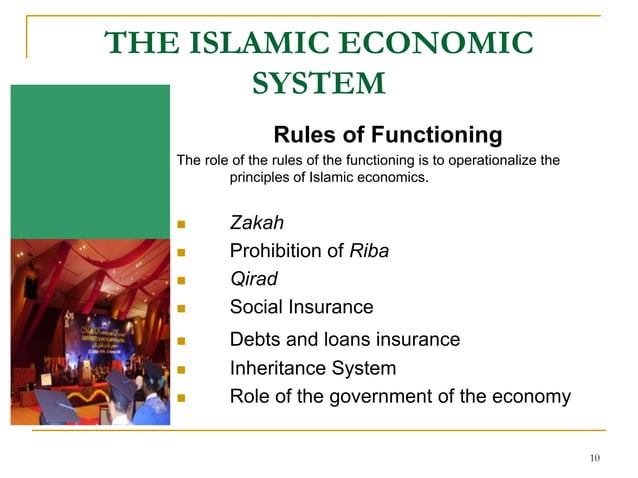
- Riba (usury): All schools uniformly prohibit interest, but the Hanafi jurists distinguish between explicit interest (riba al-fadl) and excessive profit, allowing certain markup practices under strict conditions. The Shafi'i and Maliki schools, by contrast, adopt a broader prohibition that includes many contemporary banking fees.
- Zakat and charitable giving: While the rate (usually 2.5 % of qualifying wealth) is consistent, the Maliki madhhab expands the definition of taxable assets to include certain agricultural produce, reflecting its regional agrarian roots. The Hanbali school, on the other hand, tends to emphasize the spiritual intent behind zakat rather than the precise calculation.
- Risk‑sharing contracts: Profit‑and‑loss sharing (PLS) arrangements such as mudarabah and musharakah are embraced across the board, yet the Hanafi school permits a wider array of partnership models, citing historical trade practices. Shafi'i scholars often require more explicit documentation to safeguard the parties’ rights.
- Modern financial tools: Issues like sukuk (Islamic bonds) or derivatives are hotly debated. The Maliki and Hanbali schools are generally more cautious, invoking the principle of avoiding gharar (excessive uncertainty). Hanafi jurists, referencing classical commercial contracts, are more inclined to find permissible analogues.
Integrating Madhhab Insights into Modern Policy
Governments and central banks looking to foster Islamic finance must decide which madhhab interpretations to endorse. Some nations, like Malaysia, adopt a pragmatic synthesis—drawing on Hanafi flexibility for banking products while invoking Maliki maslaha for consumer protection. Others, such as Saudi Arabia, lean heavily on Hanbali rulings, resulting in stricter compliance checks.
International standard‑setting bodies, notably the Islamic Financial Services Board (IFSB), often reference a “consensus” (ijma) that reflects a blend of madhhab opinions. This consensus approach helps create a common regulatory language, reducing the friction that could arise from divergent national rulings.
Case Study: Leasing (Ijarah) Across Schools
Leasing provides a practical illustration of madhhab nuance. The Hanafi view permits a lease‑to‑own structure where the lessee gradually acquires ownership, provided the rent reflects the asset’s usage value. The Shafi'i perspective demands a clear separation between the lease period and any subsequent sale, to avoid hidden purchase agreements. Meanwhile, the Maliki school emphasizes that the lease must not lead to exploitation, often requiring transparent market‑based rent.
When banks design Ijarah products for a multinational clientele, they typically embed optional clauses that satisfy the most stringent school—often the Shafi'i—ensuring broader acceptability.
Challenges and Ongoing Debates
One persistent challenge is the tension between tradition and innovation. Critics argue that excessive reliance on a single madhhab can stifle financial creativity, while proponents claim that adherence preserves the ethical core of Islamic economics. Moreover, the rise of fintech—blockchain, digital currencies, and AI‑driven credit scoring—poses questions that none of the classical schools anticipated.
Scholars are beginning to employ a “fiqh al‑mu‘asirah” (contemporary jurisprudence) methodology, which draws from all madhhab while allowing contextual adaptation. This hybrid approach seeks to honor the spirit of the schools without being locked into centuries‑old precedents.
FAQ
- What is the main difference between Hanafi and Maliki views on interest? The Hanafi school distinguishes between explicit interest and excessive profit, allowing certain markup practices under strict conditions, whereas the Maliki school applies a broader prohibition that includes many modern banking fees.
- Can sukuk be considered permissible in all madhhab? Sukuk are generally acceptable across the schools, but the Hanbali and Maliki traditions raise concerns about gharar (uncertainty) and require that the underlying assets be clearly defined and owned.
- How do countries decide which madhhab to follow in financial regulation? Many adopt a pragmatic blend—Malaysia mixes Hanafi flexibility with Maliki public‑interest principles, while Saudi Arabia emphasizes Hanbali rulings, leading to stricter compliance.
- Is there a unified global standard for Islamic economics? International bodies like the IFSB aim for consensus, drawing from multiple madhhab opinions to create standards that can be applied across diverse legal environments.