How to Navigate IIOxford Finance Payment Waiver: A Complete Guide
Understanding the IIOxford Finance Payment Waiver
The IIOxford Finance payment waiver is a relief mechanism designed for borrowers who encounter unexpected financial hardships. Rather than forcing a default, the program temporarily suspends or reduces payments, giving borrowers breathing room to get back on track. It’s not a free pass; the waiver typically applies to a specific period and may involve interest accrual adjustments.
Because the waiver is tied to the lender’s policies, the exact terms can differ between loan products. Still, the core idea remains the same: protect both the borrower and the lender from the ripple effects of missed payments.
Who Qualifies? Eligibility Basics
Eligibility isn’t a one‑size‑fits‑all checklist, but several common factors appear across most IIOxford Finance waivers:
- Demonstrated hardship – job loss, medical emergencies, or other documented financial setbacks.
- Good payment history – borrowers who have consistently met obligations before the hardship are viewed more favorably.
- Active loan status – the account must be current up to the point the waiver is requested.
Applicants who have previously received a waiver or who have a pattern of late payments may face stricter scrutiny. In borderline cases, the lender might ask for additional documentation, such as recent pay stubs or medical bills.
Step‑by‑Step Application Process
Getting a payment waiver from IIOxford Finance involves a handful of clear steps. Follow them closely to avoid delays.
- Gather supporting documents – bank statements, proof of income loss, or medical invoices.
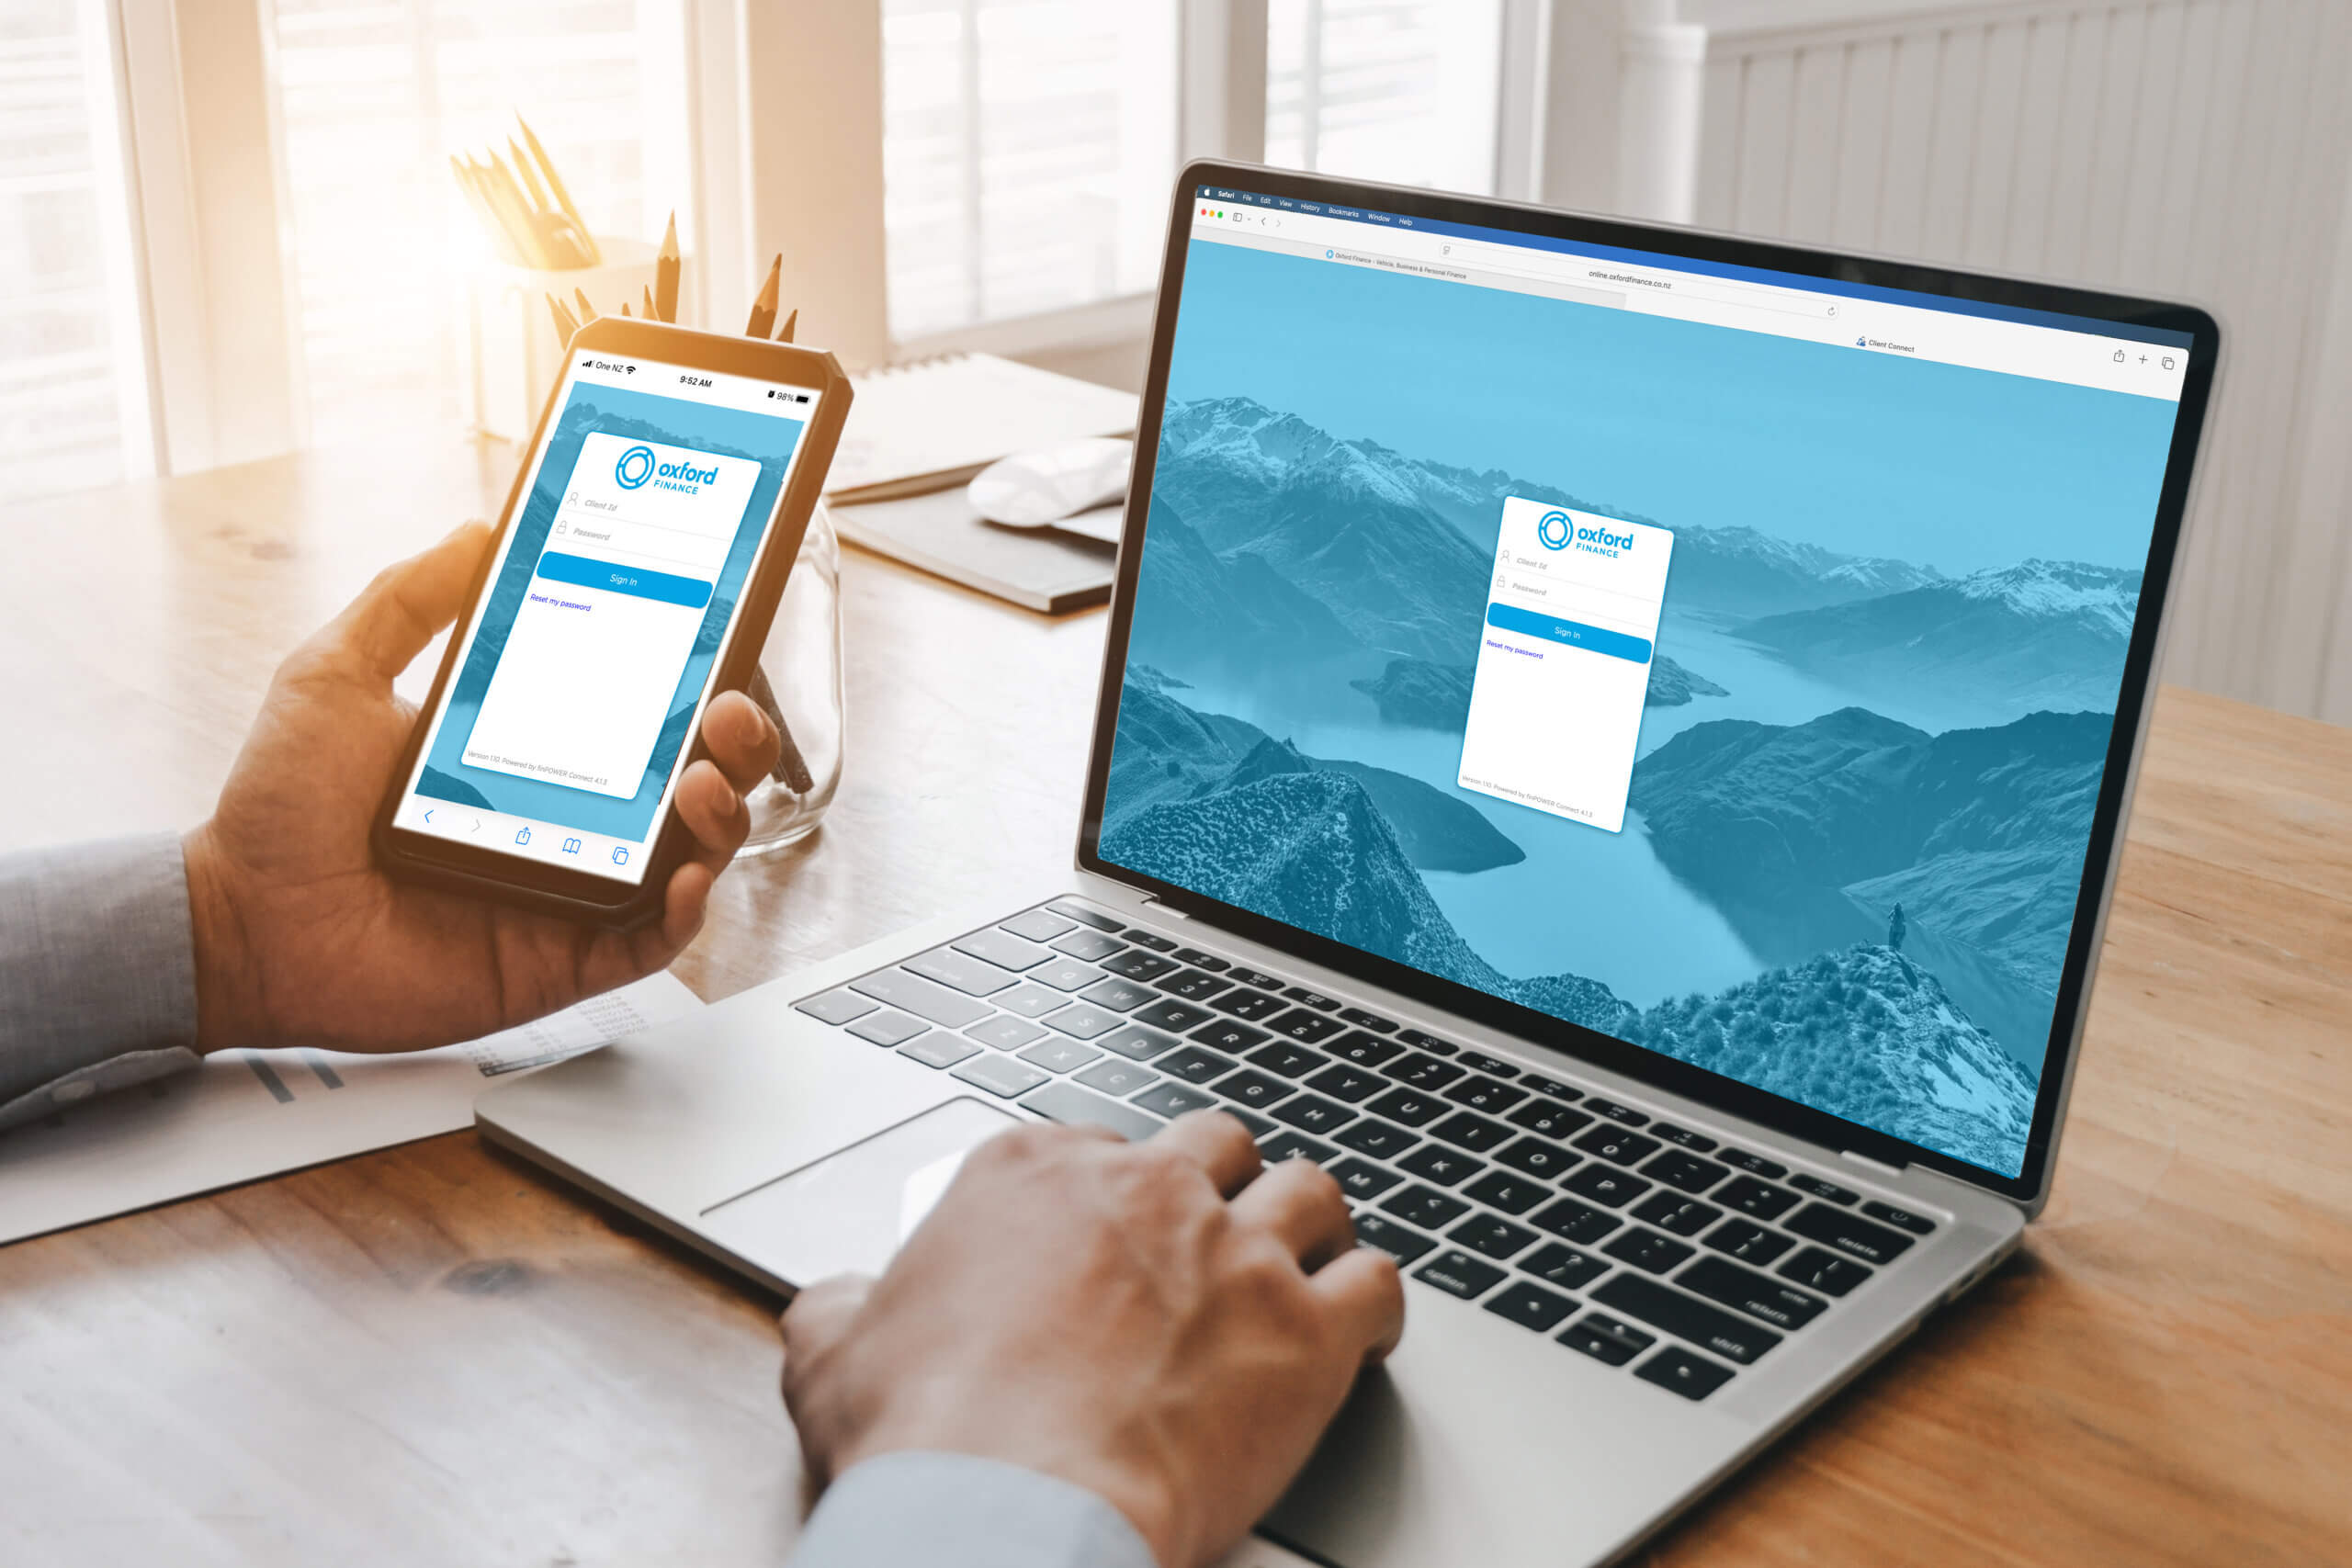
- Log into your online account – the portal usually has a “Payment Relief” or “Waiver Request” tab.
- Fill out the waiver form – answer each question honestly; vague responses often trigger follow‑up requests.
- Submit and wait for confirmation – you’ll receive an email acknowledgment, and a representative may contact you for clarification.
- Review the waiver terms – once approved, read the agreement carefully, noting any interest adjustments or repayment plans after the waiver period ends.
Most borrowers hear back within two weeks, though high‑volume periods can stretch the timeline.
Common Mistakes to Avoid
Even a well‑intentioned applicant can stumble. Here are pitfalls that frequently derail waiver requests:
- Leaving out key documents – the lender can’t verify hardship without proof.
- Missing the application window – some waivers are only offered during specific crises or fiscal quarters.
- Providing inaccurate information – discrepancies raise red flags and may result in denial.
- Assuming the waiver eliminates the debt – it only postpones or reduces payments for the approved period.
Taking a moment to double‑check each entry can save you weeks of back‑and‑forth.
Tips for a Smooth Approval
While there’s no guaranteed formula, a few best practices increase the odds of a favorable outcome.
- Contact the lender early – a quick phone call before submitting the form can clarify required documents.
- Be transparent – explain the nature of the hardship and how the waiver will help you resume regular payments.
- Keep records – retain copies of all correspondence and submitted files for future reference.
- Stay proactive after approval – set reminders for when the waiver period ends so you can adjust your budget in time.
What Happens After the Waiver Ends?
Once the waiver period expires, the loan typically reverts to its original terms, though some lenders may offer a transition plan. This could involve a temporary payment increase to catch up on missed interest, or a graduated repayment schedule that eases you back in.
If you anticipate continued difficulty, reach out before the waiver ends. Lenders often appreciate borrowers who communicate early and may extend relief or suggest alternative options, such as loan restructuring.
FAQ
Can I apply for a payment waiver if I’m already behind on payments?
Generally, the program targets borrowers who are current up to the point of hardship. If you’re already delinquent, the lender may first require you to bring the account current before considering a waiver.
Will a waiver affect my credit score?
A properly granted waiver usually does not appear as a negative item on your credit report. However, if the waiver is classified as a “payment deferral,” some credit bureaus may note the adjustment, which can be neutral or slightly positive depending on the overall credit history.
Is there a limit to how many times I can use the waiver?
Most lenders impose a limit—often one waiver per loan term—but exceptions exist for prolonged crises. Review your loan agreement or ask a representative for specifics.
Do I need to pay interest on the waived amount?
Interest policies vary. Some waivers suspend interest entirely during the period; others continue accruing but defer collection until payments resume. The terms will be spelled out in the waiver agreement.