Micron Technology Stock: Current Analysis and Future Outlook
Micron Technology (MU) stock has been on the radar of both growth‑seeking investors and seasoned analysts for its pivotal role in the memory‑chip arena. As data‑intensive applications—from cloud computing to AI‑driven devices—continue to surge, the company’s earnings trajectory feels increasingly tied to the broader semiconductor cycle. Below, we break down where the stock stands today, what’s driving its price, and how the next few quarters might shape its path.
Recent Performance Overview
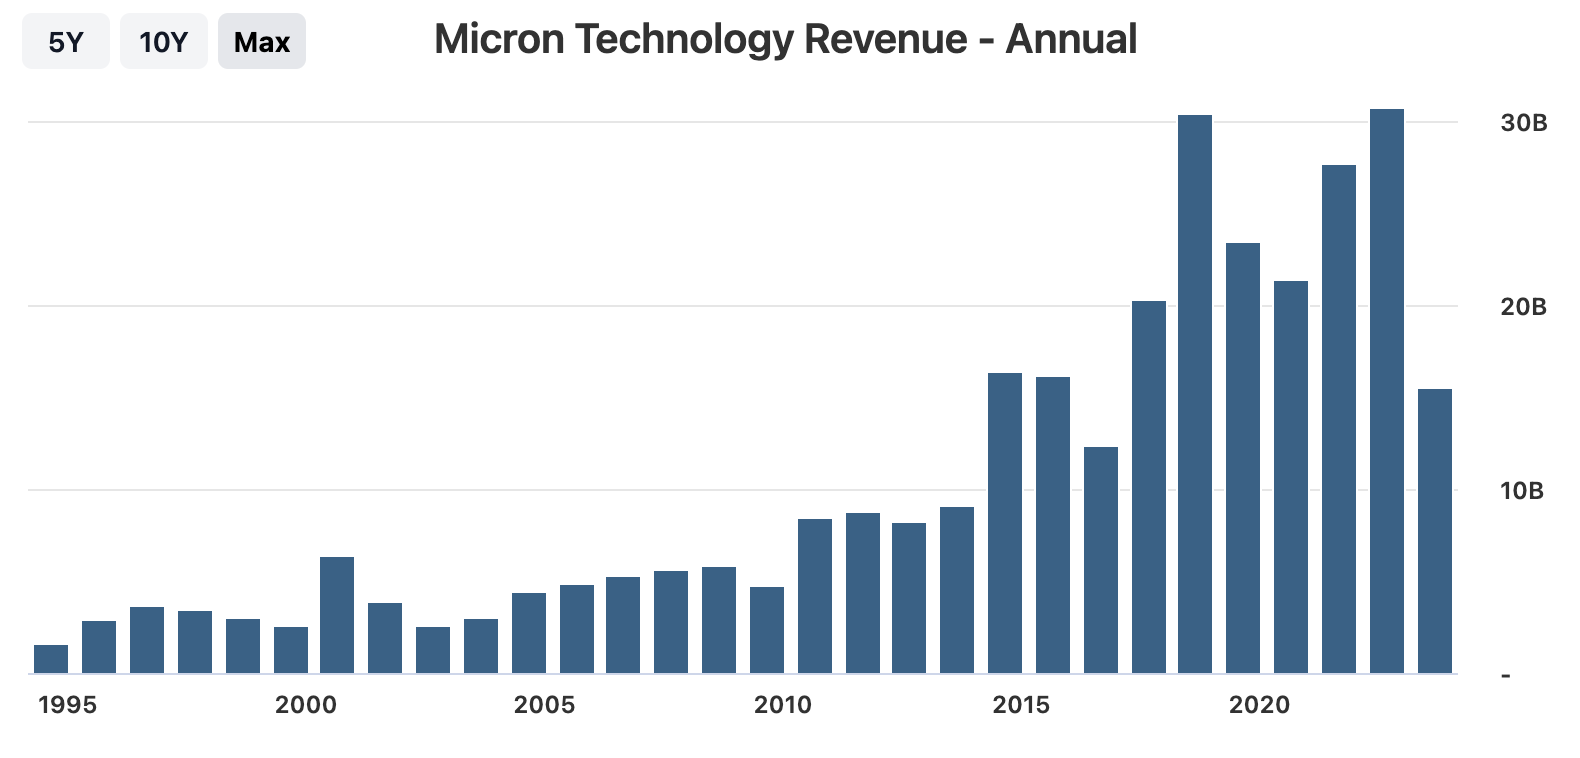
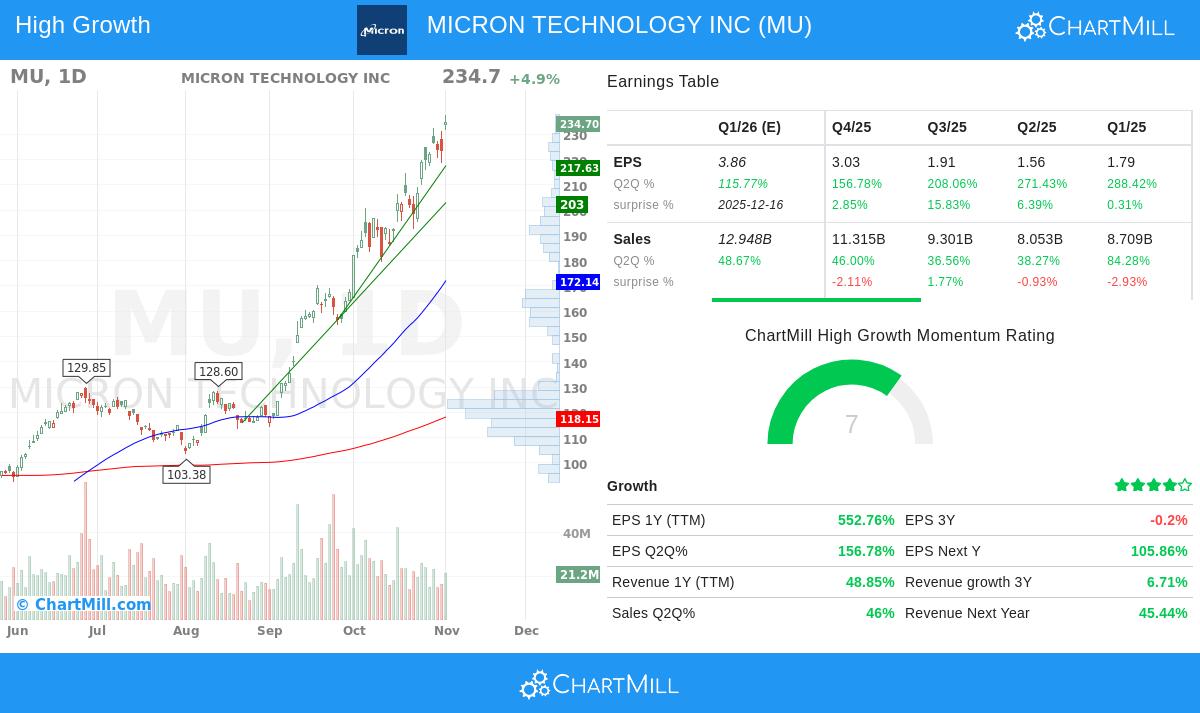
In the twelve months ending September 2024, Micron’s share price has swung roughly 15 % in either direction, reflecting the volatility typical of memory manufacturers. Revenue climbed about 9 % year‑over‑year, buoyed by higher demand for DDR5 and GDDR6 modules, while earnings per share rose modestly after a modest dip in the first half of the year.
Quarterly reports have shown a pattern: strong Q3 earnings thanks to a rebound in data‑center sales, followed by a softer Q4 as inventory adjustments took hold. The stock’s price‑to‑earnings (P/E) ratio now sits near 12×, a modest discount to the industry average, suggesting the market may be pricing in lingering supply‑chain concerns.
Micron Technology (MU) Stock Valuation Factors
Product Mix Evolution – Micron has been shifting its portfolio toward higher‑margin offerings such as 3D‑stacked NAND and specialized automotive memory. These segments command premium pricing and tend to be less cyclical than commodity DRAM.
Manufacturing Footprint – Recent investments in its new 1‑zeta fab in Singapore aim to improve yields and reduce dependence on older process nodes. While capital intensity remains high, the strategic location offers a hedge against geopolitical risks that have rattled other chipmakers.
Pricing Power – The company’s ability to raise prices for DDR5 and GDDR6 has outpaced competitors in the last two cycles, thanks to a relative scarcity of fab capacity. However, price hikes can be a double‑edged sword; they risk accelerating demand‑side substitution toward alternative memory technologies.
Risks and Challenges Ahead
Supply‑chain disruptions remain a lingering threat. Even modest delays at key equipment suppliers can ripple through Micron’s production schedule, eroding the margins that higher‑priced products promise.
Another concern is the broader macro environment. A slowdown in consumer spending, especially on gaming consoles and smartphones, could dampen demand for the memory chips that power those devices.
Lastly, competition from Samsung and SK Hynix continues to intensify. Both rivals are also expanding their advanced‑node capabilities, which could compress Micron’s market share unless it sustains its innovation cadence.
What Analysts Are Saying
Most sell‑side analysts rate Micron as a “hold” with price targets clustering between $110 and $130, roughly 8‑15 % above the current market price. The consensus outlook highlights the company’s solid balance sheet and its strategic pivot toward higher‑margin products.
On the buy‑side, a few boutique research firms argue that the market is undervaluing Micron’s upcoming 3‑D NAND roadmap, which could unlock a new revenue stream for automotive and edge‑computing applications.
Future Outlook and Investment Considerations
Looking ahead, the key question is whether Micron can sustain its pricing advantage while expanding into higher‑value segments. If demand for AI‑focused data centers continues its upward trajectory, memory demand is likely to stay robust, giving Micron a tailwind.
Investors should watch a few leading indicators: quarterly inventory levels reported by the Semiconductor Industry Association, the rollout schedule of Micron’s next‑gen NAND chips, and any policy shifts affecting global chip subsidies.
From a valuation standpoint, a forward‑looking P/E under 12 × combined with a dividend yield hovering around 0.6 % presents a modest income component for risk‑averse portfolios. However, the stock’s inherent cyclicality means it may not be suitable for those seeking low‑volatility exposure.
In summary, Micron Technology (MU) stock offers a blend of growth potential tied to emerging memory technologies and the familiar ebb‑and‑flow of the semiconductor cycle. A measured position—perhaps a modest allocation within a diversified tech basket—could let investors capture upside while buffering against inevitable market swings.
FAQ
- What is Micron's primary growth catalyst for the next 12 months? The rollout of DDR5 and 3‑D NAND products, especially for data‑center and automotive markets, is expected to drive revenue growth.
- Is Micron a good dividend investment? Micron offers a modest yield (~0.6 %) and a history of steady, though not high, dividend payouts. It may complement a growth‑oriented portfolio but isn’t a high‑yield play.
- How does Micron compare to Samsung in terms of market share? Samsung remains the clear leader in both DRAM and NAND, but Micron’s focus on niche, high‑margin segments helps narrow the gap in specific product categories.