How to Secure Loans for Sub‑600 Credit Scores and Get Approved
Having a credit score below 600 can feel like a roadblock when you need cash fast. Yet a variety of lenders still offer loans for credit scores under 600, each with its own set of requirements and trade‑offs. This guide walks you through the most realistic options, what to expect from each, and practical steps to improve your odds of approval.
Understanding Loans for Credit Scores Under 600
When a score dips into the “sub‑600” range, traditional banks often view borrowers as high‑risk. That doesn’t mean the market is empty—many specialty lenders, credit unions, and online platforms tailor products specifically for this segment. The key differences lie in interest rates, fees, and the degree of collateral required.
Why Lenders Care About Low Scores
- Higher default risk leads lenders to charge more for the privilege of borrowing.
- Limited credit history can make it harder to predict future repayment behavior.
- Regulatory caps on interest rates sometimes push lenders toward secured or short‑term products.
Loan Types Worth Considering
Below are the most common loan categories that remain accessible when your score sits under 600. Each comes with its own set of pros and cons, so read carefully before applying.
1. Secured Personal Loans
These loans require an asset—often a vehicle or a savings account—as collateral. Because the lender has something to repossess if you default, interest rates are typically lower than those of unsecured options.
- Best for: borrowers with a valuable asset and a clear repayment plan.
- Watch out: risking your collateral can be costly if you miss payments.
2. Credit Union Loans
Credit unions are member‑owned and tend to offer more forgiving terms than big banks. They may approve a sub‑600 borrower based on your relationship with the institution or your overall financial profile.
- Best for: existing members or those willing to join a local union.
- Watch out: membership eligibility can be restrictive, and loan amounts may be modest.
3. Online Installment Loans
FinTech companies often provide fixed‑payment loans over several months. Approval can be quick, and some lenders look beyond the credit score to assess income and employment stability.
- Best for: borrowers who need a predictable repayment schedule.
- Watch out: APRs can be high, and hidden fees sometimes inflate the cost.
4. Payday Alternative Loans (PALs)
Designed as a less‑expensive counterpart to traditional payday loans, PALs usually have lower interest rates and longer terms—often up to 31 days. They’re typically offered by credit unions and some community banks.
- Best for: short‑term cash gaps when you can repay within a month.
- Watch out: the loan amount is usually capped at $1,000, and missed payments can damage your credit further.
5. FHA or VA Home Equity Loans
If you own a home, government‑backed loans like FHA Title I or VA cash‑out refinancing may be available even with a low score, provided you have sufficient equity.
- Best for: homeowners needing larger sums for renovations or debt consolidation.
- Watch out: closing costs and strict property appraisal standards apply.
Steps to Boost Your Approval Chances
Even with a sub‑600 score, you can tip the scales in your favor by taking a few strategic actions before you apply.
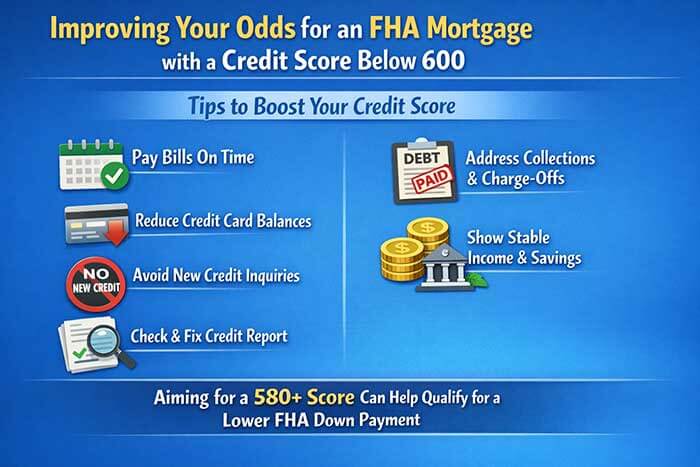
Check and Dispute Your Credit Report
Obtain a free copy of your report from the major bureaus. Errors—like a misreported late payment—can shave dozens of points off your score. Dispute inaccuracies promptly; many agencies resolve errors within 30 days.
Show Stable Income
Lenders love consistency. Providing recent pay stubs, tax returns, or bank statements that illustrate regular deposits can offset a low score. If you’re self‑employed, a few months of consistent invoicing helps.
Reduce Existing Debt
Even a modest reduction in your credit utilization ratio (the amount of credit you’re using versus your total limit) can improve both your score and your perceived risk to lenders.
Consider a Co‑Signer
A creditworthy co‑signer essentially shares the liability, allowing you to qualify for better rates. However, any missed payments affect both parties, so choose wisely.
Opt for Secured Options First
If you own a vehicle or have a savings account, a secured loan can serve as a stepping stone. Successfully repaying it can boost your credit history, opening doors to unsecured products later.
Red Flags and Pitfalls to Avoid
Low‑score borrowers are prime targets for predatory lenders. Keep an eye out for the following warning signs.
- Excessive Up‑Front Fees: Legitimate lenders may charge an origination fee, but anything that feels like a “guaranteed approval” charge is suspect.
- Unrealistically Low Interest Rates: If a rate looks too good to be true, it probably hides hidden costs or a variable rate that will skyrocket.
- Lack of Transparent Terms: A reputable lender will provide a clear repayment schedule and disclose the APR before you sign.
- Pressure Tactics: If you’re rushed into signing or told you’ll lose the offer if you hesitate, walk away.
Frequently Asked Questions
Can I get a loan with a 580 credit score?
Yes, but options are limited. Secured personal loans, credit union loans, and some online lenders still consider borrowers with scores in the high‑500s, especially if you can demonstrate steady income or offer collateral.
What’s the typical interest range for sub‑600 loans?
Interest rates can vary widely, from around 12 % APR for secured loans at credit unions to 30 % or more for unsecured online installment loans. Always compare the APR, not just the headline rate.
Will a payday loan ruin my credit?
Payday loans themselves rarely appear on credit reports, but missed payments can trigger collections, which do impact your score. Opt for PALs or other short‑term alternatives when possible.
How long does approval usually take?
Online lenders often approve within minutes to a few business days. Credit unions and secured loan applications may require a week or more due to verification of collateral and membership checks.